Category Archives: Tokenization

From Tokenized Stocks to Tokenized Royalties: What the Next Phase of RWA Investing Looks Like

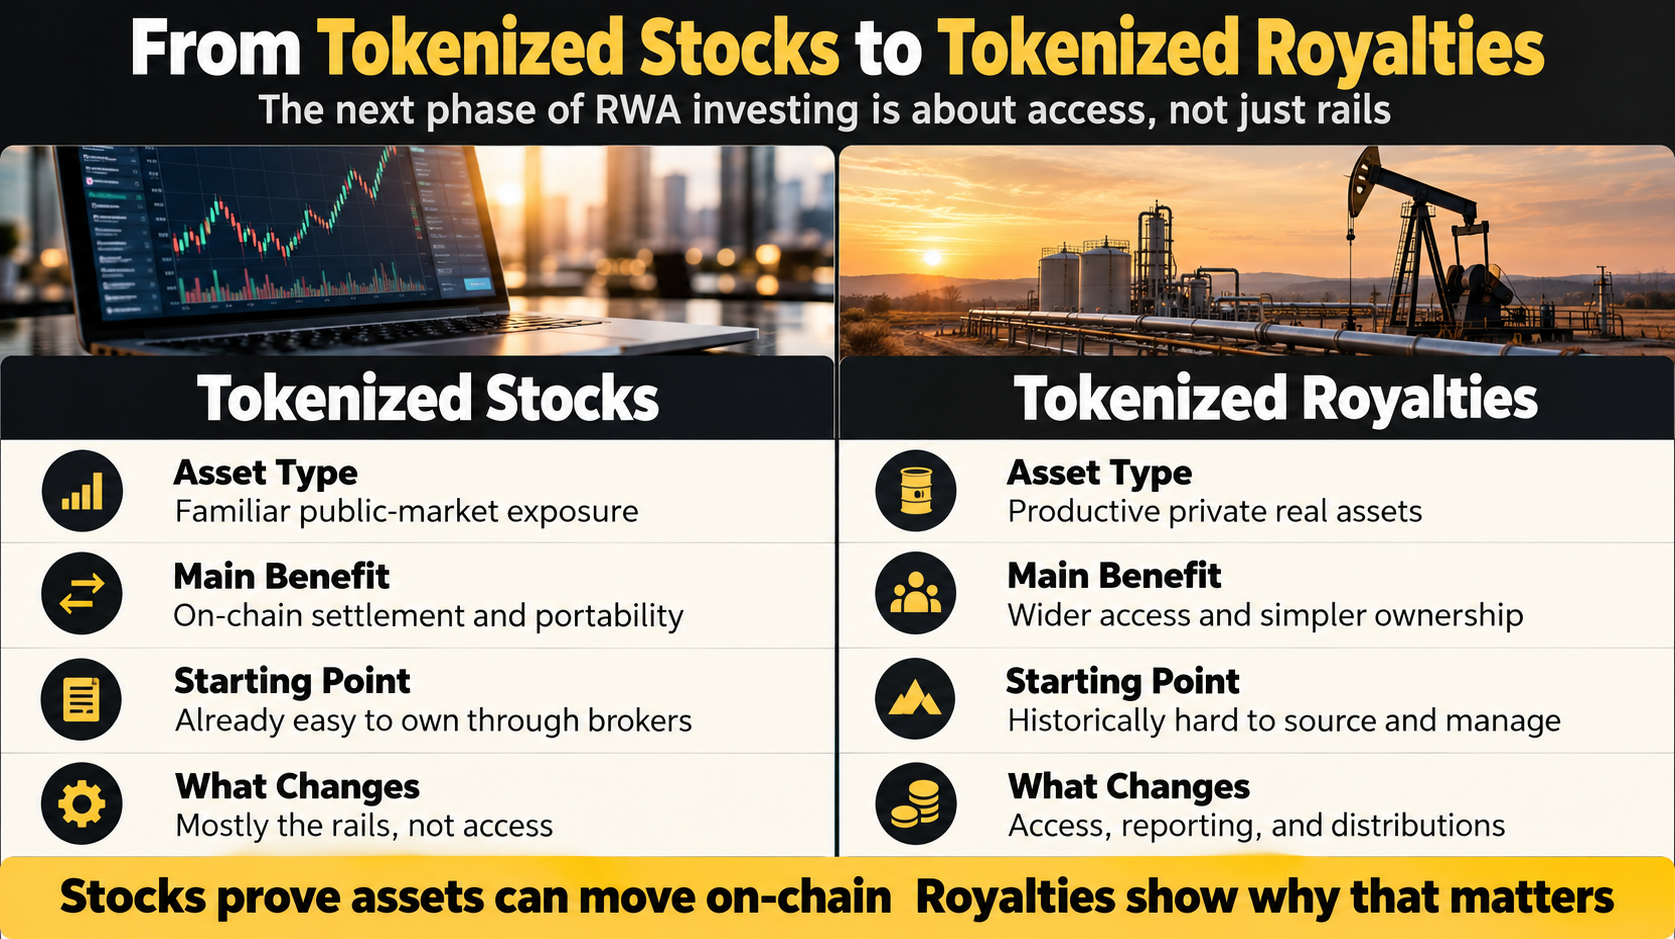
Tokenized equities are proving that traditional assets can move on-chain. The next phase is more important: using tokenization to open assets that were difficult for most investors to access in the first place.

Real-world asset tokenization has spent years trying to answer a basic question: what happens when traditional financial assets move onto blockchain infrastructure? In 2026, tokenized stocks are giving the market one of its clearest answers yet.

Public equities are increasingly being represented, transferred, and traded on-chain. U.S. regulators have also moved from discussing tokenization in the abstract to creating a framework for limited on-chain trading of certain tokenized stocks. That matters because it shows that tokenization is no longer confined to experimental pilots or crypto-native products. It is beginning to touch the core plumbing of mainstream capital markets.

But tokenized stocks may be more important as a proof point than as the final destination. Stocks are already broadly accessible, highly liquid, electronically settled, and supported by mature brokerage infrastructure. Moving them on-chain can improve portability, settlement, programmability, and global access, but the underlying asset was never especially difficult to own in the first place.

The more transformative use of tokenization begins when the underlying asset is valuable but historically hard to reach. That is where private real-world assets – including U.S. mineral and royalty interests – become especially interesting.

The next phase of RWA investing is not simply about putting more familiar assets on-chain. It is about using blockchain infrastructure where access, ownership, reporting, and distribution have historically been the hardest.

Tokenized Stocks Are Proving the Rails

The rapid growth of tokenized equities in 2026 is a meaningful signal. It tells us that investors are increasingly comfortable holding blockchain-based representations of traditional assets, interacting with digital wallets, settling through stablecoins, and moving investment exposure across on-chain venues.

It also demonstrates something more fundamental: investors care about the rights and economics behind a token, not merely the token itself. The U.S. Securities and Exchange Commission has emphasized that tokenized securities remain securities and that different tokenization structures can give holders different rights. A token can represent the security itself, an entitlement to an underlying security, or another form of economic exposure. The wrapper matters, but the legal and economic substance matters more.

That distinction is critical for the broader RWA market. A blockchain record does not automatically make an asset better. Tokenization becomes valuable when it improves the way a legitimate underlying asset is owned, transferred, administered, or understood.


Why the first wave focused on familiar assets

The earliest large-scale RWA categories were logical starting points: cash-like instruments, government debt, private credit, funds, and eventually public equities. Investors already understood how these assets worked. Tokenization could therefore focus on infrastructure – faster settlement, fractional access, programmable ownership, interoperability, and improved collateral utility – without requiring the market to learn an entirely new asset class at the same time.

Tokenized stocks fit that progression perfectly. Investors already know what Apple, Nvidia, or an equity index represents. The innovation is primarily in how that exposure can be packaged and moved.

That is an important stage of adoption, but it also highlights a limitation. If tokenization only recreates assets that investors can already buy with a few clicks through a conventional brokerage account, much of its value remains incremental rather than transformational.


The Next Phase: Tokenizing Access, Not Just Settlement

The bigger opportunity is to apply the same infrastructure to assets that have historically been constrained by geography, minimum investment size, fragmented ownership, manual administration, specialized underwriting, and limited transparency.

Those are the assets where tokenization can do more than modernize settlement. It can change the practical investment experience itself.

A useful test is simple: what friction existed before the token? If the asset was already easy to buy, easy to sell, easy to administer, and easy to understand, the token mainly changes the rails. If the asset was difficult to source, expensive to access, administratively cumbersome, and opaque after purchase, tokenization can potentially change the entire access model.


Why mineral royalties fit the RWA thesis unusually well

U.S. mineral and royalty interests are a strong example of this second category. They are interests in real property tied to the production of oil and natural gas. When production occurs, the mineral or royalty owner can receive a contractual share of the revenue. Unlike a working-interest owner, a royalty owner generally does not fund drilling and operating costs in proportion to the revenue interest.

The economic proposition is straightforward. The access model historically was not.

Private mineral ownership is highly fragmented. Individual interests can be spread across counties, states, operators, wells, leases, and title chains that require specialized expertise to evaluate. Building a diversified portfolio at meaningful scale can require substantial capital, title work, land knowledge, accounting infrastructure, operator relationships, and patience. For an investor outside the U.S. energy ecosystem, direct participation has been especially difficult.

This is exactly the kind of problem RWA tokenization is suited to address: not by changing what a mineral interest is, but by changing how an investor can access an interest in a professionally assembled portfolio of those assets.


From Price Exposure to Productive Cash Flow

There is another important difference between tokenized stocks and tokenized royalties. A tokenized stock typically gives the investor exposure to a familiar security whose value is driven primarily by the market value of the underlying company, with dividends where applicable. A tokenized royalty portfolio begins with cash generated by physical production.

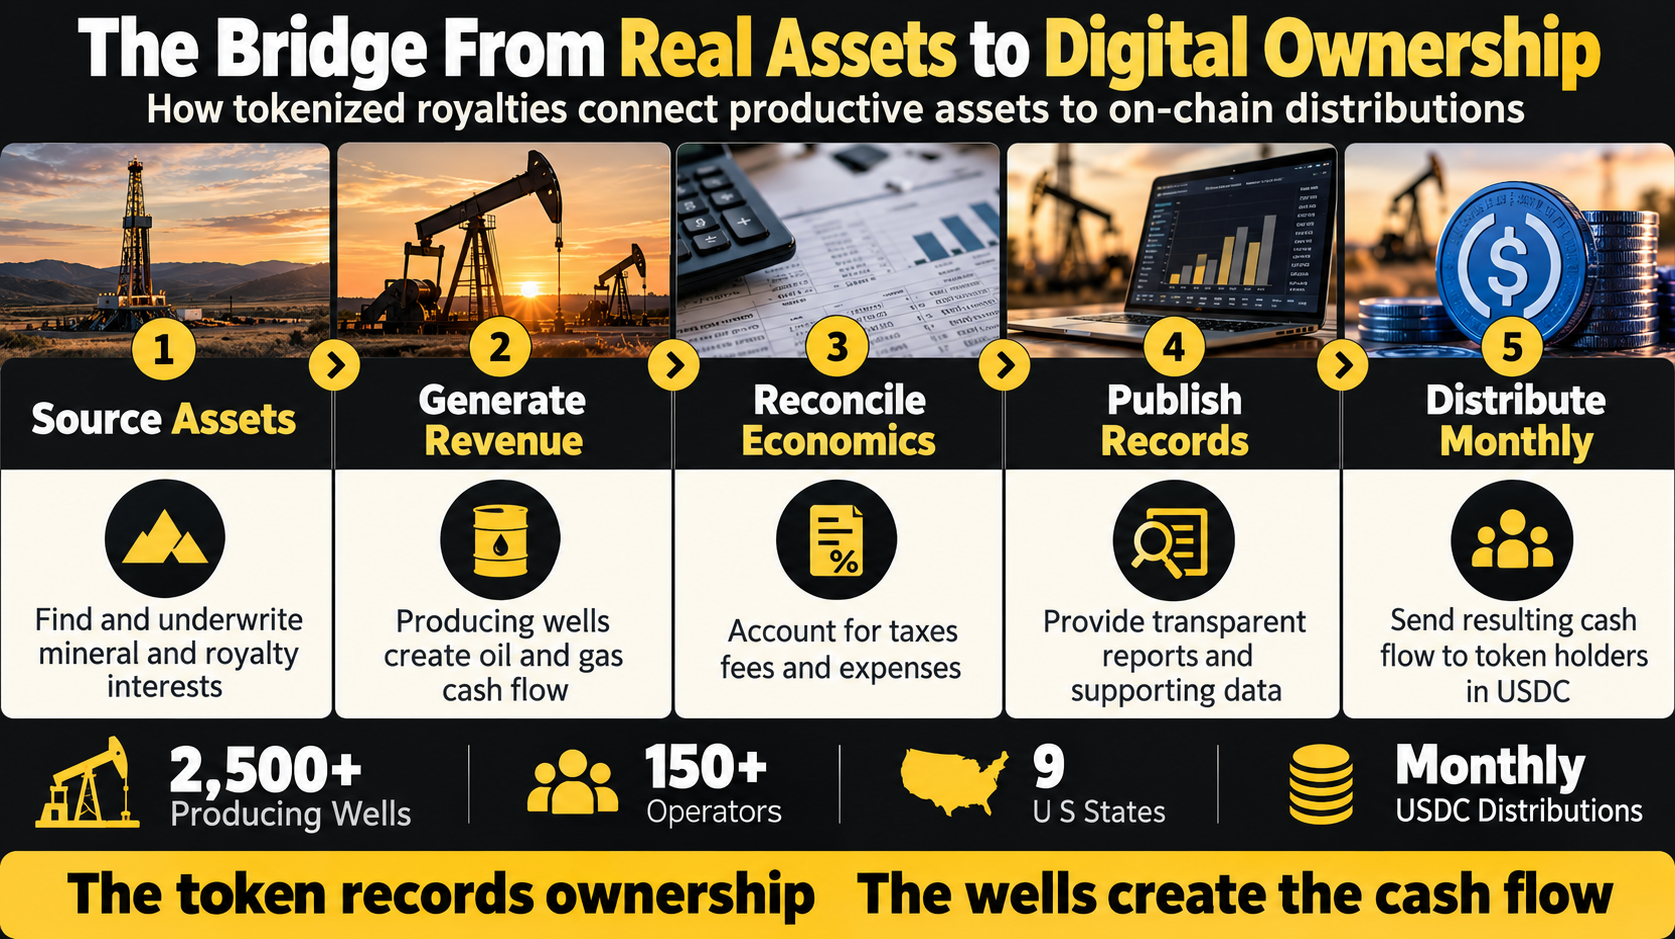
At Mineral Vault, the chain starts off-chain. Oil and natural gas are produced and sold. Purchasers and operators remit royalty revenue. Applicable property-level costs, taxes, and management fees are accounted for. The distributable amount is then paid to token holders through monthly USDC transfers.

The blockchain is therefore not the source of the yield. The wells are. Tokenization is the infrastructure that records ownership, streamlines distribution, and helps make the cash-flow trail easier to verify.

That distinction matters as the RWA market matures. The strongest RWA products will not be defined by how “crypto” they look. They will be defined by the quality of the asset, the clarity of the legal rights, the durability of the cash flow, and the transparency of the structure connecting the real-world asset to the token.


Mineral Vault I Shows What This Can Look Like in Practice

Mineral Vault I was built around this idea. The portfolio aggregates mineral and royalty exposure across more than 2,500 producing wells, more than 150 operators, 9 U.S. states, and over 10,000 gross acres. Nearly all of the underlying assets are already producing, so the investment begins with existing cash flow rather than a promise that future development must occur before distributions can start.

The first 15 months of actual cash flow published for Mineral Vault I, covering April 2025 through June 2026, totaled approximately $1.50 million net of management fees and before the effect of U.S. source-income tax withholding. Monthly distributions are delivered directly to token holders in USDC.

Just as important, each distribution is accompanied by a reporting trail. Mineral Vault publishes dividend reports, detailed summary spreadsheets, and supporting documentation for revenue and expenses through its Transparency portal. Investors can examine the off-chain cash flow and reconcile it with the on-chain distribution model.

That combination – real productive assets, digital ownership, direct-to-wallet cash distributions, and public supporting documentation – is a useful illustration of what the next phase of RWA investing can become.

The Real Innovation Is the Bridge

The phrase “real-world asset” can make it sound as if the token is the product. In reality, the most important work happens in the bridge between the physical asset and the digital instrument.

For tokenized royalties, that bridge includes:

  • Property sourcing and underwriting before an asset enters the portfolio
  • Title verification and legal documentation establishing the underlying rights
  • A defined entity and assignment structure connecting property cash flow to the tokenized vehicle
  • Ongoing collection and reconciliation of royalty revenue
  • Accounting for applicable expenses, taxes, and management fees
  • Monthly distribution of the resulting cash flow to token holders
  • Transparent records that allow investors to follow the economics from asset to wallet

This is why the next stage of RWA competition may look less like a race to issue the most tokens and more like a race to build the most trustworthy bridges between real assets and on-chain ownership.


Tokenization Should Expand the Investable Universe

The long-term promise of tokenization is not simply that every asset will have a blockchain version. It is that the investable universe can become broader, more portable, and more transparent.

Tokenized stocks demonstrate how established financial assets can interact with blockchain rails. Tokenized Treasury products demonstrate how traditional yield can move on-chain. Tokenized private credit demonstrates how institutional lending exposures can be packaged digitally. The next logical step is to bring more productive, less accessible private assets into the same environment.

Mineral royalties belong in that conversation because the underlying asset is economically mature even if the access model has historically been inefficient. The U.S. mineral market has existed for generations. What is changing is the ability to package diversified exposure into a digital security with lower minimums, programmable distributions, and a more transparent ownership and reporting framework.


Liquidity matters – but it should not be confused with instant liquidity

One of the most attractive ideas in RWA tokenization is that an asset that was historically difficult to transfer can become easier to move between eligible investors. That is a meaningful improvement, but it is important to separate transferability from guaranteed liquidity.

A token can make compliant transfers more efficient and can create the technical foundation for secondary-market activity. It cannot guarantee that a buyer will always be available, that spreads will always be tight, or that every tokenized asset will trade like a large-cap stock. The depth of any secondary market will still depend on regulation, eligibility rules, investor participation, market infrastructure, and demand for the underlying asset.

For that reason, the best RWA thesis is not “tokenization makes everything liquid.” It is “tokenization can make historically cumbersome assets more transferable, more interoperable, and easier to administer while preserving the economic reality of the asset underneath.”


The Token Matters Less Than What It Represents

As more stocks, funds, credit products, commodities, real estate interests, and private assets move on-chain, investors will need a more sophisticated framework for comparing them. “RWA” will become too broad a label to say much on its own.

The questions that matter will look increasingly familiar:

  • What exactly does the token represent?
  • What legal rights does the holder have?
  • What produces the underlying cash flow?
  • What are the principal risks to that cash flow?
  • How diversified is the underlying portfolio?
  • What fees, taxes, and deductions apply?
  • How transparent is the reporting?
  • What happens if the tokenization platform, custodian, or service provider changes?

That is healthy. The maturation of RWA investing should move attention away from the novelty of tokenization and toward the quality of the asset and structure being tokenized.


What the next phase of RWA investing looks like

Tokenized stocks are an important milestone because they normalize the idea that conventional financial exposure can live on-chain. They also help regulators, institutions, exchanges, and investors learn how digital ownership can work at scale.

But the most consequential phase may come next. Once the rails are accepted, tokenization can be applied to assets where legacy finance has left more friction in place: private real estate, infrastructure, specialty credit, commodities, energy assets, and other cash-flowing property rights that have traditionally been reserved for institutions, insiders, or investors with large amounts of capital.

That is the opportunity Mineral Vault was designed around. We are not using blockchain to invent a new source of value. We are using it to open a long-established U.S. real-asset market in a more accessible, transparent, and programmable format.

Tokenized stocks show that assets can move on-chain. Tokenized royalties show why some assets may be more valuable once they get there.

Final Thoughts

The RWA market is moving quickly from proof of concept toward a broader question of portfolio construction. Investors will increasingly be able to hold public equities, fixed income, private credit, real estate, commodities, and alternative income assets within the same digital environment.

In that world, the winners will not necessarily be the assets with the most recognizable tickers. They may be the assets where tokenization creates the greatest difference between the old investment experience and the new one.

U.S. mineral royalties are a compelling example. They are backed by real property rights, linked to real energy production, capable of producing recurring cash flow, and historically difficult for most investors to access directly. Tokenization does not change those fundamentals. It makes them easier to reach, easier to administer, and easier to understand.

That is what the next phase of RWA investing should be about: not putting blockchain in front of every existing asset, but using blockchain where it can genuinely widen access to productive real-world value.

Disclaimer: This article is educational in nature and should not be considered investment, tax, or legal advice.
Oil Barrel With Tokens

Why Tokenize Mineral Interests?

In addition to opening the lucrative mineral interest asset class to a global investor base, Mineral Vault’s vision to tokenize mineral interests also resolves numerous issues plaguing mineral interest ownership & transfer in the United States presently. Let’s take a closer look:

Mineral Ownership Challenges Resolved By Tokenization

As of 2024, the process of ownership transfer in the mineral and royalty interest sector is extremely inefficient for several reasons, all of which are resolved by tokenization.  The major inefficiencies in the process are related to title verification and transfer administration.

Title Verification Challenges

When acquiring interests in mineral properties directly, prospective buyers face tremendous title verification challenges that prevent most non-professional buyers from participating in the marketplace.  These challenges include:

  • No title insurance product. The complete lack of a title insurance product for mineral & royalty interests means that title must be independently verified by the purchaser to their satisfaction. In layman’s terms, the buyer of a mineral property is likely to lose most or all of their money if the person they are paying to purchase the property later turns out to have not been the rightful owner of the property in the first place! To resolve this problem, generally “landmen” are hired to review courthouse records to create a chain of title, gather the related documents from the courthouse, and provide a summary “mineral ownership report”.  These can optionally be given to a title attorney who will review them in-depth and create a “title opinion” which is a more detailed report listing title inadequacies and any issues which should be addressed before closing.  Neither of these vendors provide any title guarantee or insurance and all title risk is borne by the purchaser of the mineral property.


  • Extreme title complexity. The complexity of the title review process is increasing exponentially as time passes and ownership chains become longer and longer, with an exponentially increasing ownership base, caused by the fact that deceased owners often leave their interests to multiple children or grandchildren, simply subdividing the ownership interest between them.  This phenomena doesn’t typically happen with surface interests, since it is difficult for more than one person to “use” or benefit from the surface interests — mineral interests, however, don’t have any utility other than the investment-like income they can provide from production.  As a result of the fact that mineral interests are often subdivided from estates (and therefore handled more like shares of stock than traditional surface real estate), most property parcels in high-production areas of the U.S. have between 20-50 distinct owners, each with a different percentage ownership in the property parcel.


THE TOKENIZATION SOLUTION: Title Verification Challenges

From the moment that mineral interests are placed on the blockchain and traded as tokens (whether individually or in aggregate, as in the initial Mineral Vault offerings), the blockchain resolves issues of provenance completely.  The blockchain is a verifiable, public ledger of ownership, meaning new owners can be 100% sure that the seller of the tokenized interest they are purchasing is in fact the rightful owner.

But what about title defects which arise from before the time the particular mineral interest was tokenized, debasing the token’s representative ownership in property from the very beginning?

At Mineral Vault, our thesis is that the party which tokenizes mineral interests in the first place should bear the risk of any title failures which predate the tokenization. Thus, for title failures occurring prior to tokenization of the assets, Mineral Vault has provided a title guarantee, ensuring investors are “made whole” relative to their original investment in the property if title failure happens*.

The result of the blockchain solution is that the title verification aspects of the ownership transfer process are completely seamless and void of the need for expensive landmen and title attorneys.

Transfer Administration Challenges

In addition to the title challenges associated with direct mineral interest investment, there are numerous administrative hurdles encountered by would-be owners:

  • Deed Drafting & Filing. Similar to the process for acquiring a surface interest, to purchase a mineral or royalty interest, at least one Mineral Deed, Mineral & Royalty Conveyance, Assignment, or similar document must be created by an attorney or other professional, then executed and notarized.  It must then be filed at the county courthouse wherein the property resides, a process which can take up to 2 weeks or more if the recordings must be mailed in.


  • Purchaser Notification & Pay Status Update. Upon successful filing of the deed/conveyance, a copy of the recorded document must then be provided to the purchaser(s) of the oil, gas, or other hydrocarbons actively being produced by the wells on the acreage acquired.  This document evidences the transfer and allows the purchaser to place the new owner “in pay” on the wells, meaning that the new owner begins to receive the royalty checks for revenue.  In practice, this process can take 3-6 months or more with many purchasers whose transfer departments are understaffed, overworked, and severely backlogged due to the increasing number of transfers happening each year.
    • The “purchaser” is often the operator of the well(s) in question but does not have to be, as some small operators do not purchase the hydrocarbons produced by the wells they drill themselves, but rather sign a purchase agreement with a separate vendor who handles the hydrocarbon pick-up/transportation from the wellhead and royalty payments to all mineral owners in accordance with the amounts picked up.  Note also that, if a well produces both oil and natural gas, for instance, there could be a different purchaser for each of the commodity types, meaning one for oil and one for natural gas.  In this scenario, both purchasers must be notified separately.


  • Tax Authority Notification & Tax Record Update. Also upon successful filing of the deed/conveyance, a copy of the recorded document must also be sent to the tax authority responsible for the property in question — for example, the Midland County Central Appraisal District (“Midland CAD”) for a property located in Midland County, Texas.  The tax authority will review the document and place the new owner “in-tax” on the property in question, ensuring that the new owner receives the property tax bills rather than the previous owner.  This is necessary to ensure that property taxes are paid (whereas they might not be if the bills continue to be mailed to the previous owner, who knows they sold the property) because if the taxes go unpaid for a long enough period, the properties can ultimately be sold out from under the new owner at the courthouse steps in a Tax Sale. Therefore, ensuring that the tax records show the new owner as the record owner for tax purposes is a critically important step in the transfer process.  In practice, the governmental tax authorities often use vendors to manage and update their tax records, many of whom are understaffed and unresponsive to update requests, meaning many tax record updates can take 3-6 months or more, similar to pay status updates.


THE TOKENIZATION SOLUTION: Transfer Administration Challenges

All of the administrative challenges described above are rendered totally unnecessary & void by tokenization.  From the perspective of all of the entities above (the county courthouse, the purchasers, and the tax authorities), the property is still owned by the same party, which is the tokenized entity (also referred to as the “Special Purpose Vehicle” or “SPV”), and only ownership interest in the SPV is actually being exchanged.  This in effect transfers ownership interest in the mineral property, but does so in a way which totally circumvents the need for the administrative steps traditionally required and thereby greatly improves property liquidity.

Conclusion

The application of blockchain technology to the mineral interest ownership tracking & transfer  process will introduce many desperately-needed efficiencies to an industry that is rapidly increasing in both scale and complexity.

In the future, after many Mineral Vault offerings and the resulting tokenization of a tremendous quantity of mineral & royalty interests, we believe tokenization can be the “grand / ultimate” solution to the crisis of mineral interest title & transfer in the United States.  In the process, we will not only resolve the title and administrative challenges described in this article, but we will also open investment in these assets to millions of new investors globally, further improving their liquidity.

*The “make whole” amount is an amount, in USD, determined by portfolio manager Mineral Vault LLC. The calculation shall be an amount of value attributed to the property at time of token issuance less any payments received on the property by token holders since that time.  See also the “Disclaimers” section of the website at mineralvault.io.

Why Private Mineral Ownership Is So Rare Globally – And Why That Matters

When most people think about oil, gas, and other valuable underground resources, they picture governments, national oil companies, and state-controlled licensing regimes. In most of the world, that is the correct mental model. The subsurface belongs to the state, and private parties participate only through concessions, leases, joint ventures, or service contracts granted by the government.

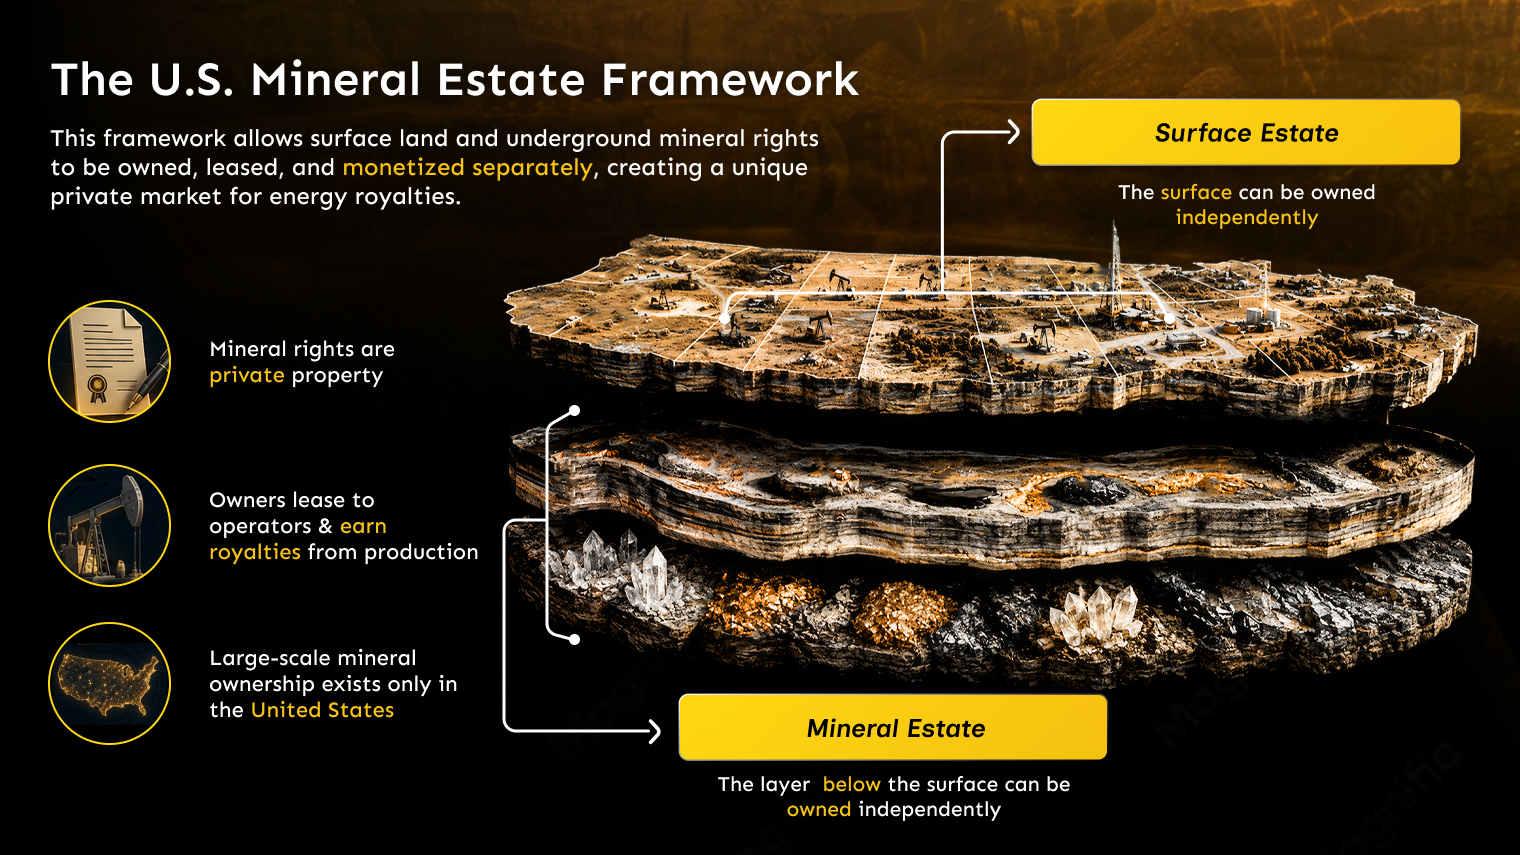
That is precisely why the United States remains so unusual. Here, mineral rights can be privately owned, sold, inherited, severed from the surface estate, and leased to operators in exchange for royalties. That legal structure created an investable market that is rare on a global scale: a market where private owners can hold long-duration rights to underground resources and receive income when those resources are developed.

For Mineral Vault, that is not just an interesting legal footnote. It is the foundation of our asset class. Private mineral ownership is what makes American oil and gas royalties both so compelling and so historically difficult to access. And once investors understand why this ownership model is rare, they also understand why bringing it on-chain matters.


The global rule: governments control the subsurface

Across much of the world, subsurface resources are treated as sovereign assets. Even when surface land is privately owned, the oil, gas, or mineral estate below it is often reserved to the national or regional government. Companies can still explore and produce, but they do so through state-issued rights, negotiated contracts, and regulatory frameworks that do not create the same large-scale private ownership market seen in parts of the United States.

This matters because it changes the entire ownership chain. In a state-dominant system, investors usually gain exposure through public equities, sovereign-linked ventures, production-sharing agreements, debt instruments, or direct corporate ownership in operating companies. What they generally do not gain is a broad market of privately owned mineral interests that can be aggregated, transferred, leased, and monetized over decades the way U.S. mineral properties can.

That is why private mineral ownership at scale is so rare globally. It is not simply a matter of geology. It is a matter of property law, legal history, and the way different countries chose to allocate economic rights in natural resources.


The U.S. exception: a private market in the mineral estate

The United States developed a very different framework. In most producing regions, the mineral estate can be treated as a separate form of real property. That means the rights below the ground can be owned independently from the surface above it. A parcel can therefore have one owner for the surface and another for the minerals. Those mineral rights can be sold, transferred, inherited, and leased in their own right.

That separability is one of the defining features of the asset class. In practical terms, it means mineral owners do not have to drill wells themselves to benefit economically. They can lease their mineral interests to operators, collect an upfront lease bonus in many cases, and then receive an ongoing royalty tied to production if development occurs. In other words, they own the property interest while the operator takes on the capital-intensive work of drilling, completing, and producing the well.

This is also why mineral and royalty interests have long occupied a category of their own:

  • They share some traits with real estate, because they are real property interests.
  • They share some traits with income assets, because they can generate recurring cash flow.
  • They share some traits with commodity-linked derivatives, because revenue rises and falls with production volumes and commodity prices.

…but mineral and royalty interests are not reducible to any one of these buckets.

It is important to keep the nuance intact here. Not every mineral resource in the United States is privately owned. Federal lands, many state-owned lands, tribal lands, and offshore federal resources follow different legal frameworks. The point is not that every American resource is private. The point is that the United States has a deep and scalable private minerals market – especially onshore – that is unusual among major producing nations.


Why this rarity creates both value and friction

Whenever an asset class is both economically attractive and structurally unusual, two things tend to happen at once: the asset becomes valuable, and access becomes messy. That is exactly what happened in mineral interests.

On the value side, private mineral ownership gives investors direct participation in American energy production without requiring them to operate wells. When high-quality mineral interests are leased and producing, owners can receive long-duration royalty income with meaningful inflation linkage because hydrocarbons are sold into real commodity markets. In many structures, the mineral owner also avoids most of the drilling and operating costs borne by the operator.

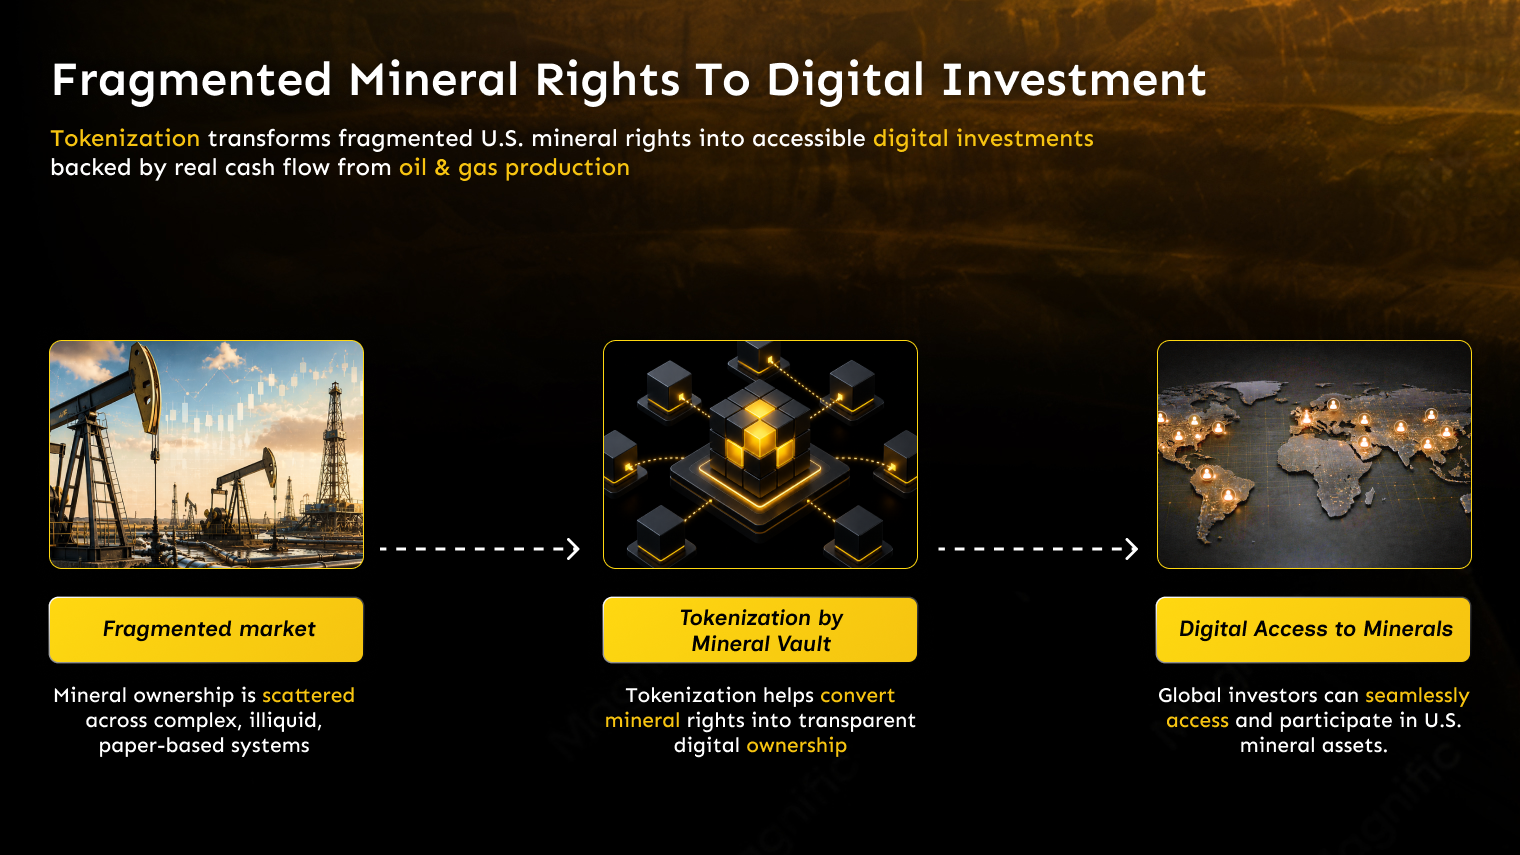
On the friction side, the market developed in a way that was highly fragmented, paper-heavy, and relationship-driven. Mineral rights have often passed through generations, trusts, estates, family partitions, and thousands of individual transactions. Ownership records can be scattered across county courthouses and title files. Minimum investment sizes have historically been high. Liquidity has been limited. And for investors outside the United States, the barriers have been even higher because the asset class itself is so tied to a uniquely American property system.

This combination is exactly why mineral interests have remained under-owned by the broader global investment market. It is not because the cash flow characteristics are weak. It is because the access path has traditionally been too narrow, too technical, and too operationally burdensome for most investors to navigate.


Why it matters to investors

For investors, the global rarity of private mineral ownership matters because rarity shapes portfolio opportunity. If an asset class exists at scale in only one major jurisdiction, and if access to that asset class has historically been difficult, then the investors who can access it efficiently may be seeing a genuinely differentiated source of return.

Mineral and royalty interests provide exposure to real-world production cash flow rather than to the earnings of an operator or the coupon stream of a bond. They can offer monthly income, inflation-sensitive revenue, long-duration underlying property exposure, and upside from future leasing or drilling activity on the acreage. At the same time, they are not the same thing as direct working interests in wells, where capital calls and operating costs can materially change the risk profile.

That distinction matters even more in a modern portfolio. Many investors already understand stocks, bonds, and listed real estate. Far fewer have access to a real-asset income stream tied directly to U.S. energy production while remaining generally non-cost-bearing at the mineral-owner level. That is part of what makes the asset class so compelling once it can be accessed cleanly.


Why it matters to Mineral Vault

Mineral Vault was built around the idea that a rare, high-quality asset class becomes dramatically more powerful when access frictions are reduced. Mineral Vault I brings together a large, diversified portfolio of U.S. mineral and royalty interests spanning more than 2,500 producing wells, more than 10,000 gross acres, 150-plus operators, and 9 U.S. states. That scale matters because it moves investors away from the concentration risk of a single property or operator and toward a broader stream of American energy cash flow.

Just as importantly, Mineral Vault does not present mineral ownership as a novelty. It presents it as infrastructure for a better investment experience. Through tokenization, a historically fragmented and paper-based market can be transformed into a digital ownership record with clearer provenance, lower administrative friction, easier transferability within the applicable compliance framework, and monthly digital distributions tied to real underlying cash flow.

That bridge from old-world property rights to modern financial rails is what makes the topic so relevant today. The underlying legal foundation is not new. Private mineral ownership in the U.S. has existed for generations. What is new is the ability to package that ownership into a structure that is more transparent, more accessible, and more usable for a broader class of investors, including investors outside the traditional U.S. mineral-rights ecosystem.


Historically, if a global investor wanted exposure to U.S. mineral interests, the practical obstacles were substantial. The investor had to understand title, legal documentation, jurisdictional structuring, operator reporting, cash distribution mechanics, and a market that often moved through specialist networks rather than broad digital marketplaces. Even sophisticated investors frequently chose not to engage, not because the asset class lacked merit, but because the ownership system was too inefficient.

Tokenization changes that equation. Once the underlying mineral interests are properly aggregated and structured, digital ownership records can replace much of the transfer friction that made the asset class so cumbersome. On-chain records can improve provenance after issuance and transfer. Compliance tooling can help preserve lawful access pathways. Reporting can become more standardized and more visible. And cash flow can be distributed in a way that better matches the expectations of modern digital investors.

This is where the rarity of private mineral ownership becomes more than an interesting educational topic. It becomes a strategic advantage. If the United States is one of the only places where this type of asset exists at meaningful scale, and if Mineral Vault can make that asset class more legible and accessible to a global audience, then tokenization is not a cosmetic wrapper. It is the enabling layer that converts a rare property-rights system into an investable digital experience.


A more precise way to think about the opportunity

It is tempting to reduce the story to a simple headline: the U.S. is unique, therefore mineral royalties are valuable. But the better way to think about it is more specific. The rarity matters because it concentrates a distinctive ownership model inside one major market. That ownership model produces a real-asset income stream that most global investors have never had efficient access to. And because access has been so inefficient, the market has historically remained narrower than the underlying economic value would suggest.

Mineral Vault exists to close that gap. By combining professionally managed U.S. mineral and royalty interests with blockchain-native issuance, transparent reporting, and digital distributions, Mineral Vault is not inventing a new asset class. It is opening an old and highly differentiated one to a modern investor base.


Final Thoughts

Private mineral ownership is rare globally because most legal systems reserve subsurface value for the state. The United States developed differently, creating a market where mineral rights can be privately held, leased, and monetized at scale. That difference has made American mineral interests both powerful and hard to reach.

Why does that matter? Because rare ownership structures create rare investment opportunities – but only if investors can actually access them. Mineral Vault is built on the belief that U.S. mineral and royalty interests deserve a broader audience, and that tokenization can finally provide the access layer this asset class has always lacked.

In that sense, the story is larger than mineral rights alone. It is about what happens when a uniquely American property system meets global digital finance. And that is exactly where the next chapter of this asset class begins.

Why a Diversified Royalty Portfolio Behaves Differently From a Single Well Bet

Most people think oil and gas investing means backing one well and watching it decline. That is the wrong lens for a large royalty portfolio. Scale, diversification, and, most importantly, reserve replacement can make thousands of wells behave very differently from a single declining asset.

When investors first hear “oil and gas,” many picture the classic one-well story: a well gets drilled, production starts strong, and then the investment lives or dies based on that one well’s decline curve. That mental model is intuitive, but it breaks down when you move from one well to a broad portfolio of mineral and royalty interests.

Mineral Vault I is not a single borehole, a single operator, or a single county. It is a diversified portfolio tied to more than 2,500 producing wells across 9 U.S. states and more than 150 operators, with additional wells able to come online on presently leased or newly leased acreage over time. That scale changes the economics, the risk profile, and even the way depletion behaves.

Most discussions of diversification stop at the obvious factors: more wells, more states, more operators, and broader commodity exposure. Those all matter. But in a portfolio this large, the deeper difference is that reserve replacement itself becomes material. New wells coming online across the acreage can meaningfully offset declines from older wells, which has the effect of lessening the portfolio’s overall depletion rate versus what investors would expect from a single-well bet.

Key idea: In a portfolio this large, reserve replacement becomes a material factor. Recurring new wells can help soften the aggregate decline curve, which is why portfolio-level depletion often looks very different from single-well depletion. 


The Single-Well Mindset Is Inherently Binary

In a single-well investment, nearly every major variable is concentrated in one place. There is one operator making the key decisions, one drilling and completion design, one production profile, one set of local field conditions, and one timeline for decline. If that well underperforms, experiences downtime, gets shut in, or reaches marginal economics sooner than expected, the investor feels it almost immediately.

That is what makes a single-well bet so binary. There is very little internal diversification to absorb disappointment. If the well is a star, results can be excellent. If it is average, or worse, there is nowhere else inside the asset base for the investor to hide.

This is also why depletion feels so immediate in a single-well structure. Most wells produce strongest early in life and then decline over time. Without meaningful nearby development or additional assets around it, the investment story eventually becomes a simple countdown of shrinking volumes and shrinking cash flow.


The Obvious Benefits of Diversification Are Real

A diversified royalty portfolio changes that picture right away.

First, it spreads risk across GEOGRAPHY. Production coming from multiple states and basins reduces dependence on any one local market, weather event, regulatory issue, or infrastructure bottleneck.

Second, it spreads risk across OPERATORS. When a portfolio is tied to more than 150 operators instead of one, the budget decisions, execution quality, or operational delays of any single company have a far smaller effect on the total cash-flow base.

Third, it spreads COMMODITY exposure. Some wells may be more oil-weighted, others more natural-gas-weighted. That matters because oil and gas do not always move in lockstep, and a broader mix can make revenue streams more resilient across different commodity cycles.

Fourth, it spreads decline profiles across TIME. In a large portfolio, not every well is at the same stage of life. Some wells are mature and steady. Some are newer and more productive. Some may be temporarily offline. Others may not even be drilled yet. That staggered mix alone makes the aggregate production curve look very different from the sharp decline profile investors tend to associate with a single well.

Those are the obvious reasons a portfolio behaves differently. But they are still only part of the story.


Reserve Replacement Is Where Scale Really Matters

The most overlooked distinction is reserve replacement.

In simple terms, reserve replacement means new production is added while older production is naturally declining. In the context of mineral and royalty interests, that can happen when operators drill additional wells on acreage already held inside the portfolio, or when newly leased acreage is developed and begins producing.

In a small asset base, reserve replacement may be little more than a possibility. In a portfolio this large, it becomes a material factor in how the asset behaves over time.

That is because Mineral Vault’s portfolio is not just a collection of existing wells. It is a collection of existing wells plus additional development potential. Mineral Vault has repeatedly emphasized that the properties selected for inclusion are intended to have healthy current cash flow while also having surrounding acreage where new wells could be drilled in the future. Its public materials also note that additional wells on presently leased or newly leased acreage may come online over time.

That point is more important than it may seem at first glance.

In a one-well deal, the investment is usually tied to one decline curve. In a large royalty portfolio, the asset base is more dynamic. Older wells may be fading, but other parts of the acreage can still be developed. Some wells may go offline when operators decide production is no longer economic. At the same time, new wells may be drilled elsewhere across the portfolio. The investment is not standing still.

And that is where scale changes everything. The timing of future drilling is never perfectly uniform, and not every property will see new development on the same schedule. But across a portfolio with thousands of wells, broad acreage, and many active operators, new wells are not just a one-time upside surprise. They can become a recurring feature of the portfolio’s life.


Why Reserve Replacement Lessens the Overall Depletion Rate

It is important to be clear about what this means and what it does not mean.

It does not mean depletion disappears. Every oil and gas asset depletes over time. Mineral Vault has been transparent about that reality, which is one reason the flagship structure is term-limited rather than perpetual.

What reserve replacement does mean is that depletion at the portfolio level can look very different from depletion at the single-well level.

Think about a single well as one production curve. After initial production, that curve generally trends downward. Now think about a large royalty portfolio as hundreds or thousands of overlapping production curves. Some are declining. Some are flattening out. Some are newer and still relatively strong. Some are future drilling locations that may become producing wells later. When enough new wells continue coming online across the asset base, they inject fresh production into the system and soften the speed at which the total portfolio declines.

This is exactly why reserve replacement becomes material in a portfolio of this size. The real question is no longer, “Will this one well deplete?” Of course it will. The better question is, “How much of that depletion can be offset by new development elsewhere in the portfolio?”

At the broader U.S. industry level, this is already how production is sustained. Older wells decline, while new wells are drilled to offset a meaningful share of that decline. A large mineral and royalty portfolio with exposure to active basins benefits from that same basic operating reality. It does not need every well to remain strong forever. It needs enough new development across the system to keep the aggregate decline shallower than it would be in a single-asset structure.

That is the key distinction. A single well is a static story. A large portfolio is a moving system.


Why This Matters for Mineral Vault Investors

Mineral Vault I draws revenue from more than 2,500 producing wells across 9 states, more than 10,000 gross acres, and more than 150 operators. The portfolio was assembled through more than 350 separate transactions, and future development potential was part of the selection process from the beginning.

That combination matters because reserve replacement is much harder to achieve in a narrow asset base. If an investor owns interest in one or two wells, there may be little room for additional drilling, little operator diversity, and very little ability for fresh production elsewhere to offset decline. In a portfolio with this kind of scale, the odds are much higher that some part of the acreage is being actively evaluated, leased, drilled, or brought online over time.

Just as important, Mineral Vault’s public property-selection criteria emphasize that the portfolio is largely made up of mineral and royalty interests rather than cost-bearing working interests. That means successful new development can add fresh revenue to the portfolio without requiring token holders to fund drilling capital themselves.

This also changes how investors should think about income durability. The portfolio’s cash flow does not depend on one well staying exceptional. It depends on the broader health of a large and diversified system of producing and developable acreage.

That is a major difference.

It means investors are not simply buying a smaller ticket into the same old single-well experience. They are buying exposure to a broader royalty ecosystem where current production, operator diversity, commodity mix, and reserve replacement all interact month after month.

It is also one of the reasons Mineral Vault’s model is especially well suited to tokenization. Tokenization makes ownership more accessible and distributions more transparent, but the underlying asset still matters most. A narrow, binary asset is narrow and binary whether it is on-chain or off-chain. A diversified royalty portfolio, by contrast, brings structural advantages before tokenization even enters the picture.


The Bottom Line

Most people understand the first layer of why a diversified royalty portfolio behaves differently from a single well bet. They understand geography, operator mix, and commodity diversification.

The more important layer is reserve replacement.

In a portfolio this large, reserve replacement becomes a material factor. New wells coming online across the acreage can lessen the portfolio’s overall depletion rate by introducing fresh production as older wells decline. That does not eliminate risk, and it does not mean cash flow will never trend lower over time. But it does mean the portfolio is typically less binary, less synchronized, and less dependent on the fate of any one well than a traditional single-well wager.

A single well is one asset and one curve.

A diversified royalty portfolio is an ecosystem.

And when that ecosystem includes current production, undeveloped acreage, broad operator exposure, and recurring opportunities for new wells to come online, it can behave very differently, and far more resiliently, than the classic one-well oil and gas bet.

How Trust Is Established in Tokenized Oil & Gas Assets

Trust has always been at the heart of oil & gas mineral ownership.

For generations, mineral owners in the United States have relied on trust — trust in land records, trust in operators, and trust that royalty payments would arrive as expected. These systems worked, but they were often slow, difficult to understand, and mired with paperwork.

As mineral interests move onchain, the technology may be new, but the need for trust stays the same. In fact, it matters more than ever.

At Mineral Vault, tokenization is not about changing what mineral ownership is. It is about making a well‑understood asset easier to see, manage, and trust — a critical step in bringing this asset class to a global investor base.


Trust Starts With the Asset, Not the Technology

Technology doesn’t create trust by itself.

Oil & gas mineral interests have value because they’re tied to real production.

Crude oil, natural gas and other hydrocarbons are produced and sold from existing wells every month, and this will continue until the amount of produced hydrocarbons each month is totally miniscule. That reality exists whether records are kept on paper or on a blockchain.

Tokenization doesn’t change this reality, or the geology, production decline curve, or commodity prices paid by purchasers.

What it does change is how clearly these things can be tracked — and as a result, understood — with the aid of the blockchain and blockchain-based reporting.


Transparency Is Now the Standard

In the past, mineral information lived in filing cabinets, county offices, and mailed statements. It often took time and effort to understand what you owned and what you were owed.

Today, expectations are higher. Mineral owners want clear records, visible ownership, and straightforward reporting. Transparency is no longer optional — it is expected.

This is why Mineral Vault has created our Transparency portal — a growing series of links to transparent data relating to the entirety of information connected to our Mineral Vault I properties (and beyond).  This data includes support for all revenue & expense data which is used to calculate monthly dividend payments, as well as all operator/purchaser-supplied production data and revenue statements for the 2,500+ producing wells across the offering’s 10,000+ gross acres, all publicly-accessible.

This data, in aggregate, allows for a holistic audit of every penny flowing into our out of the Mineral Vault I SPV.

In time, these records along with the token ownership records themselves will all be blockchain-indexed.


Why This Matters Today

Energy markets remain uncertain, and capital now moves across borders more easily than ever.

For prospective mineral interest investors, Mineral Vault tokens offers a seamless and transparent avenue of exposure to these assets, all without compromising the best financial characteristics of the assets themselves.

The Future of Energy Investing: Why Tokenized Royalties Will Reshape Global Portfolios in 2026

As 2025 comes to a close, one thing has become clear across financial markets: real-world assets (RWAs) are no longer a niche experiment. They are becoming a foundational component of the digital economy — and energy assets, specifically U.S. oil & gas royalties, are emerging as one of the most compelling sectors within this new landscape.

For decades, mineral and royalty interests were accessible only to insiders with specialized knowledge, patience for administrative complexity, and substantial capital. Today, that gate is opening. Tokenization is transforming historically fragmented, paper-based assets into programmable, auditable financial instruments that can be accessed globally.

As we look toward 2026, here’s why we believe tokenized energy royalties are set to reshape investor portfolios worldwide — and how Mineral Vault is leading that shift.


1. Yield Is King — and Energy Royalties Deliver It Reliably

For years, global investors chased yield in low-rate environments. Now, with interest rates expected to ease and traditional income assets repricing, attention is shifting back to stable, real-asset-backed yield.

Mineral and royalty interests are uniquely positioned:

  • They generate monthly cash flow.

  • They are inflation-protected because hydrocarbons sell at spot commodity prices.

  • They carry no operating costs for the royalty owner.

  • They often produce income for multiple decades.

In an era defined by macro uncertainty, tokenized royalties offer something rare: predictable yield from a physical economic activity — American energy production.


2. Tokenization Is Moving From Idea to Infrastructure

2025 marked the transition from experimentation to execution. Tokenization platforms, custodians, and L1/L2 ecosystems matured dramatically. Plume Network, which Mineral Vault leverages for token issuance and yield distribution, represents this shift — infrastructure purpose-built for RWAs rather than retrofitted for them.

As RWA-native chains scale, we expect 2026 to bring:

  • Instant secondary liquidity for historically illiquid assets

  • Smarter compliance primitives that preserve global accessibility

  • Unified yield markets where tokenized energy, real estate, and credit coexist

  • Institutional on-ramps that normalize digital ownership of private assets

Energy royalties, with their steady cash flow and clean legal structure, fit this world perfectly.


3. Global Investors Want Access to U.S. Energy — But Haven’t Had It

The United States is the world’s largest producer of both oil and natural gas. Yet for international investors, gaining exposure to U.S. mineral interests has historically been nearly impossible due to:

  • Title verification challenges

  • Administrative complexity

  • High minimum investments

  • Jurisdictional barriers

  • Illiquidity

Tokenization removes these barriers in a single stroke. Today, an investor in Singapore, Brazil, or Europe can access U.S. energy royalty cash flow through a compliant, digital instrument that automates:

  • Ownership

  • Cash distribution

  • Documentation

  • Record-keeping

This is unprecedented — and demand is rising fast.


4. Portfolio Construction Is Being Redefined

Investors increasingly want assets that behave differently from traditional stocks and bonds.
Portfolios of oil & gas royalties like Mineral Vault I provide:

  • Zero correlation to equities

  • Zero correlation to credit spreads

  • Direct participation in energy production

  • Monthly off-chain → on-chain conversions of real cash flow

  • Geographic and operator diversification across thousands of wells

As global allocators reassess risk frameworks for 2026, real-asset income — especially programmable income — will become a larger share of modern portfolios.


5. 2026 Will Mark the Rise of Tokenized Cash Flow Products

Most RWAs today are tokenized claims or representations of traditional assets. Tokenized royalties are different — they are native cash-flowing assets, generating monthly yield with no intermediary conversion needed.

This positions them for:

  • Vault integrations

  • Yield-bearing DeFi primitives

  • Structured products

  • Collateralization

  • Instant composability

In other words, tokenized energy royalties aren’t just assets — they are building blocks for entirely new financial products.

Tokenized real-world yield is the next frontier, and energy royalties are poised to sit at the center of it.


6. Mineral Vault’s Role in the Next Wave

Mineral Vault I validated something powerful:
that private energy assets can be aggregated, de-risked, tokenized, and distributed globally — while generating healthy, transparent monthly income.

Mineral Vault I spans properties including:

  • 2,500+ producing wells

  • 10,000+ gross acres

  • 150+ operators

  • 9 U.S. states

  • Diverse commodity exposure (crude oil, natural gas, et al)

  • Automated USDC yield

…and the model is no longer theoretical. It works — at scale.

As we prepare for Mineral Vault II and additional offerings in 2026 and beyond, our focus is clear:
expand access, deepen diversification, and continue building the world’s premier marketplace for tokenized oil & gas properties.


Closing Thought: A New Financial Era Is Beginning

2024 was the year RWAs gained attention.
2025 was the year infrastructure matured.
2026 will be the year real cash-flowing assets dominate on-chain finance.

Energy royalties — stable, inflation-protected, and operationally passive — are uniquely suited to lead that shift.

By bridging the physical production of American energy with the precision of blockchain finance, Mineral Vault is not just observing the future of investing — We are building it.