Author Archives: Karan Apoorv

From Tokenized Stocks to Tokenized Royalties: What the Next Phase of RWA Investing Looks Like

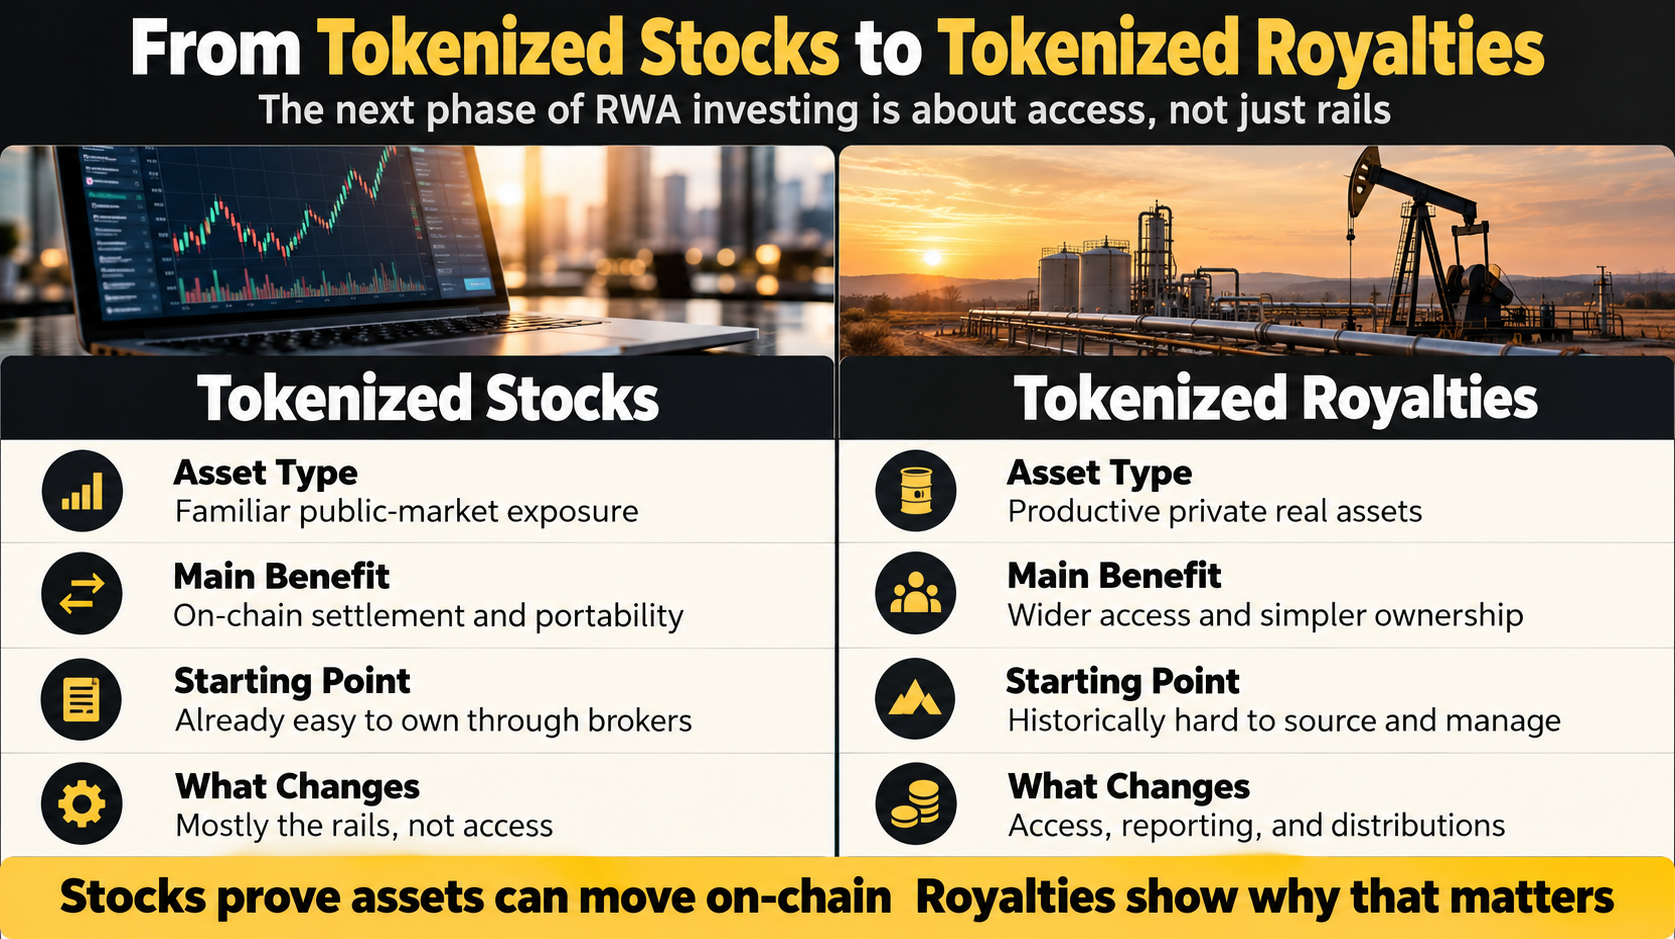
Tokenized equities are proving that traditional assets can move on-chain. The next phase is more important: using tokenization to open assets that were difficult for most investors to access in the first place.

Real-world asset tokenization has spent years trying to answer a basic question: what happens when traditional financial assets move onto blockchain infrastructure? In 2026, tokenized stocks are giving the market one of its clearest answers yet.

Public equities are increasingly being represented, transferred, and traded on-chain. U.S. regulators have also moved from discussing tokenization in the abstract to creating a framework for limited on-chain trading of certain tokenized stocks. That matters because it shows that tokenization is no longer confined to experimental pilots or crypto-native products. It is beginning to touch the core plumbing of mainstream capital markets.

But tokenized stocks may be more important as a proof point than as the final destination. Stocks are already broadly accessible, highly liquid, electronically settled, and supported by mature brokerage infrastructure. Moving them on-chain can improve portability, settlement, programmability, and global access, but the underlying asset was never especially difficult to own in the first place.

The more transformative use of tokenization begins when the underlying asset is valuable but historically hard to reach. That is where private real-world assets – including U.S. mineral and royalty interests – become especially interesting.

The next phase of RWA investing is not simply about putting more familiar assets on-chain. It is about using blockchain infrastructure where access, ownership, reporting, and distribution have historically been the hardest.

Tokenized Stocks Are Proving the Rails

The rapid growth of tokenized equities in 2026 is a meaningful signal. It tells us that investors are increasingly comfortable holding blockchain-based representations of traditional assets, interacting with digital wallets, settling through stablecoins, and moving investment exposure across on-chain venues.

It also demonstrates something more fundamental: investors care about the rights and economics behind a token, not merely the token itself. The U.S. Securities and Exchange Commission has emphasized that tokenized securities remain securities and that different tokenization structures can give holders different rights. A token can represent the security itself, an entitlement to an underlying security, or another form of economic exposure. The wrapper matters, but the legal and economic substance matters more.

That distinction is critical for the broader RWA market. A blockchain record does not automatically make an asset better. Tokenization becomes valuable when it improves the way a legitimate underlying asset is owned, transferred, administered, or understood.


Why the first wave focused on familiar assets

The earliest large-scale RWA categories were logical starting points: cash-like instruments, government debt, private credit, funds, and eventually public equities. Investors already understood how these assets worked. Tokenization could therefore focus on infrastructure – faster settlement, fractional access, programmable ownership, interoperability, and improved collateral utility – without requiring the market to learn an entirely new asset class at the same time.

Tokenized stocks fit that progression perfectly. Investors already know what Apple, Nvidia, or an equity index represents. The innovation is primarily in how that exposure can be packaged and moved.

That is an important stage of adoption, but it also highlights a limitation. If tokenization only recreates assets that investors can already buy with a few clicks through a conventional brokerage account, much of its value remains incremental rather than transformational.


The Next Phase: Tokenizing Access, Not Just Settlement

The bigger opportunity is to apply the same infrastructure to assets that have historically been constrained by geography, minimum investment size, fragmented ownership, manual administration, specialized underwriting, and limited transparency.

Those are the assets where tokenization can do more than modernize settlement. It can change the practical investment experience itself.

A useful test is simple: what friction existed before the token? If the asset was already easy to buy, easy to sell, easy to administer, and easy to understand, the token mainly changes the rails. If the asset was difficult to source, expensive to access, administratively cumbersome, and opaque after purchase, tokenization can potentially change the entire access model.


Why mineral royalties fit the RWA thesis unusually well

U.S. mineral and royalty interests are a strong example of this second category. They are interests in real property tied to the production of oil and natural gas. When production occurs, the mineral or royalty owner can receive a contractual share of the revenue. Unlike a working-interest owner, a royalty owner generally does not fund drilling and operating costs in proportion to the revenue interest.

The economic proposition is straightforward. The access model historically was not.

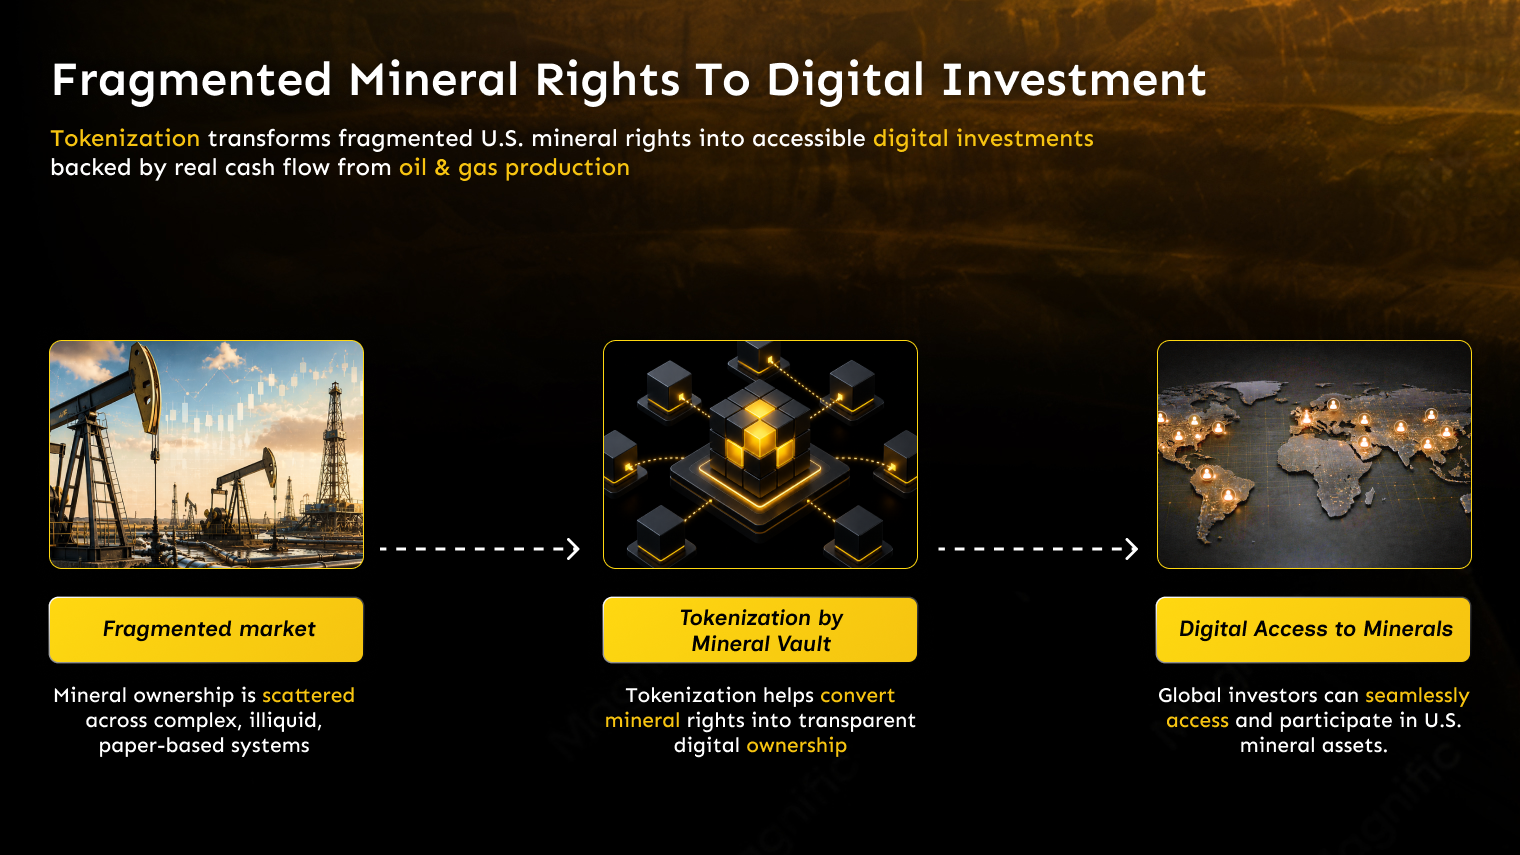
Private mineral ownership is highly fragmented. Individual interests can be spread across counties, states, operators, wells, leases, and title chains that require specialized expertise to evaluate. Building a diversified portfolio at meaningful scale can require substantial capital, title work, land knowledge, accounting infrastructure, operator relationships, and patience. For an investor outside the U.S. energy ecosystem, direct participation has been especially difficult.

This is exactly the kind of problem RWA tokenization is suited to address: not by changing what a mineral interest is, but by changing how an investor can access an interest in a professionally assembled portfolio of those assets.


From Price Exposure to Productive Cash Flow

There is another important difference between tokenized stocks and tokenized royalties. A tokenized stock typically gives the investor exposure to a familiar security whose value is driven primarily by the market value of the underlying company, with dividends where applicable. A tokenized royalty portfolio begins with cash generated by physical production.

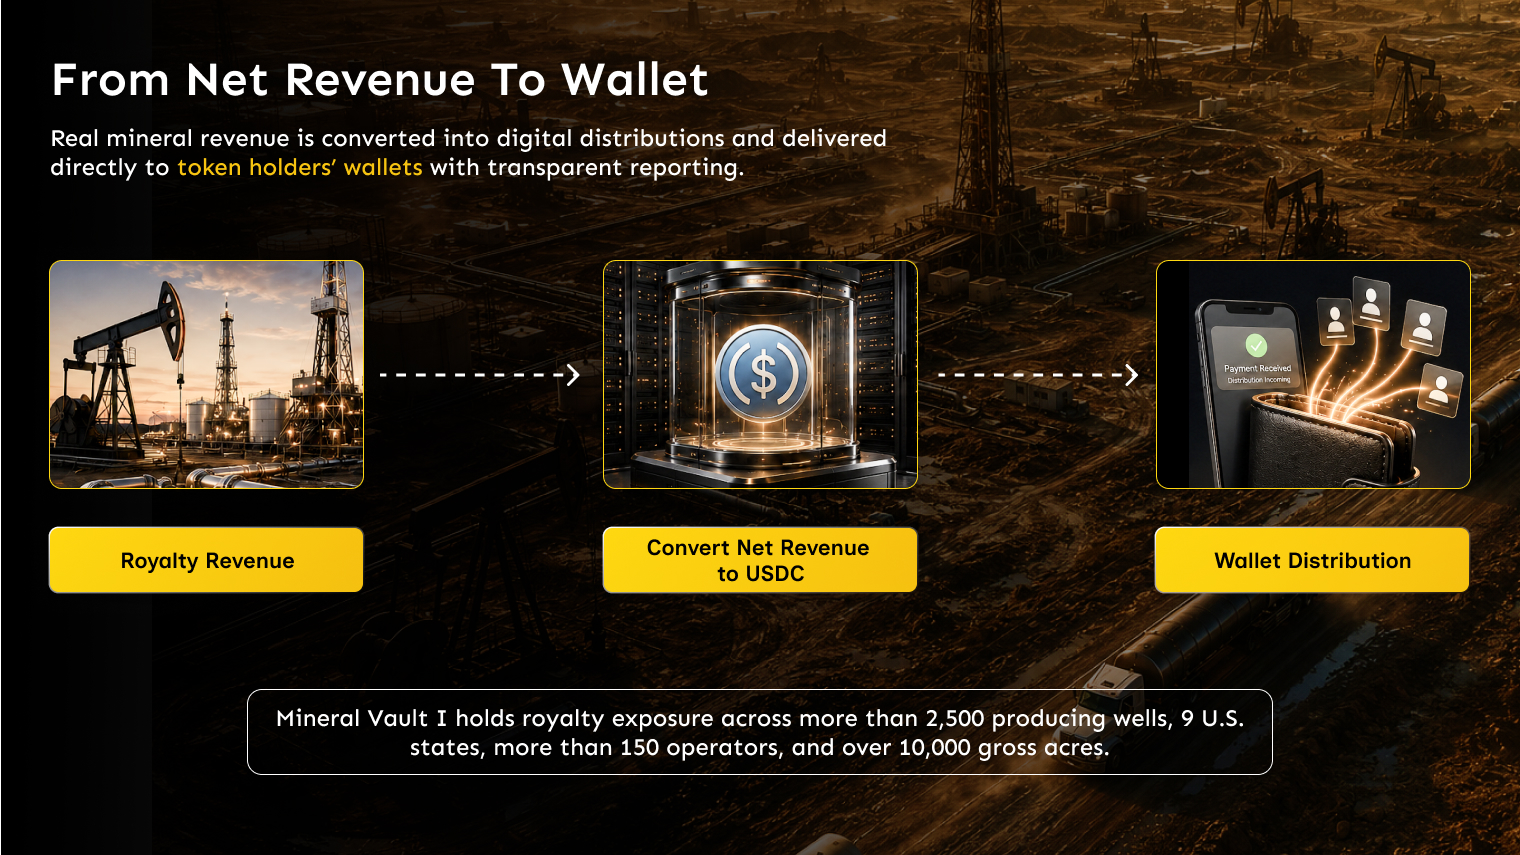
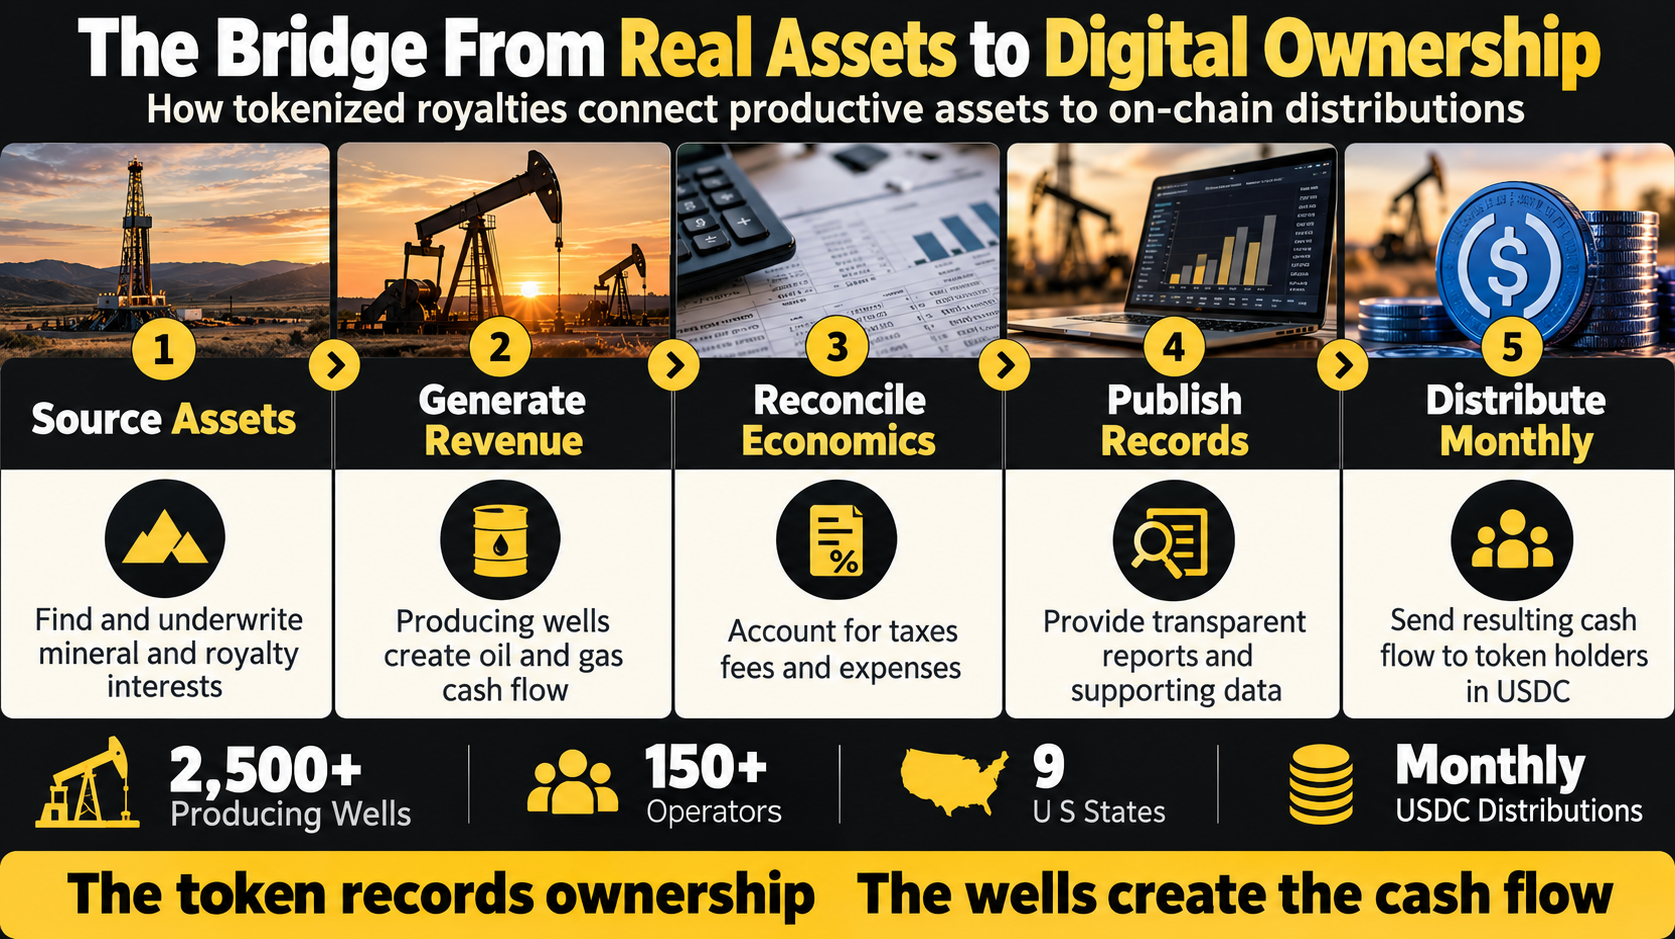
At Mineral Vault, the chain starts off-chain. Oil and natural gas are produced and sold. Purchasers and operators remit royalty revenue. Applicable property-level costs, taxes, and management fees are accounted for. The distributable amount is then paid to token holders through monthly USDC transfers.

The blockchain is therefore not the source of the yield. The wells are. Tokenization is the infrastructure that records ownership, streamlines distribution, and helps make the cash-flow trail easier to verify.

That distinction matters as the RWA market matures. The strongest RWA products will not be defined by how “crypto” they look. They will be defined by the quality of the asset, the clarity of the legal rights, the durability of the cash flow, and the transparency of the structure connecting the real-world asset to the token.


Mineral Vault I Shows What This Can Look Like in Practice

Mineral Vault I was built around this idea. The portfolio aggregates mineral and royalty exposure across more than 2,500 producing wells, more than 150 operators, 9 U.S. states, and over 10,000 gross acres. Nearly all of the underlying assets are already producing, so the investment begins with existing cash flow rather than a promise that future development must occur before distributions can start.

The first 15 months of actual cash flow published for Mineral Vault I, covering April 2025 through June 2026, totaled approximately $1.50 million net of management fees and before the effect of U.S. source-income tax withholding. Monthly distributions are delivered directly to token holders in USDC.

Just as important, each distribution is accompanied by a reporting trail. Mineral Vault publishes dividend reports, detailed summary spreadsheets, and supporting documentation for revenue and expenses through its Transparency portal. Investors can examine the off-chain cash flow and reconcile it with the on-chain distribution model.

That combination – real productive assets, digital ownership, direct-to-wallet cash distributions, and public supporting documentation – is a useful illustration of what the next phase of RWA investing can become.

The Real Innovation Is the Bridge

The phrase “real-world asset” can make it sound as if the token is the product. In reality, the most important work happens in the bridge between the physical asset and the digital instrument.

For tokenized royalties, that bridge includes:

  • Property sourcing and underwriting before an asset enters the portfolio
  • Title verification and legal documentation establishing the underlying rights
  • A defined entity and assignment structure connecting property cash flow to the tokenized vehicle
  • Ongoing collection and reconciliation of royalty revenue
  • Accounting for applicable expenses, taxes, and management fees
  • Monthly distribution of the resulting cash flow to token holders
  • Transparent records that allow investors to follow the economics from asset to wallet

This is why the next stage of RWA competition may look less like a race to issue the most tokens and more like a race to build the most trustworthy bridges between real assets and on-chain ownership.


Tokenization Should Expand the Investable Universe

The long-term promise of tokenization is not simply that every asset will have a blockchain version. It is that the investable universe can become broader, more portable, and more transparent.

Tokenized stocks demonstrate how established financial assets can interact with blockchain rails. Tokenized Treasury products demonstrate how traditional yield can move on-chain. Tokenized private credit demonstrates how institutional lending exposures can be packaged digitally. The next logical step is to bring more productive, less accessible private assets into the same environment.

Mineral royalties belong in that conversation because the underlying asset is economically mature even if the access model has historically been inefficient. The U.S. mineral market has existed for generations. What is changing is the ability to package diversified exposure into a digital security with lower minimums, programmable distributions, and a more transparent ownership and reporting framework.


Liquidity matters – but it should not be confused with instant liquidity

One of the most attractive ideas in RWA tokenization is that an asset that was historically difficult to transfer can become easier to move between eligible investors. That is a meaningful improvement, but it is important to separate transferability from guaranteed liquidity.

A token can make compliant transfers more efficient and can create the technical foundation for secondary-market activity. It cannot guarantee that a buyer will always be available, that spreads will always be tight, or that every tokenized asset will trade like a large-cap stock. The depth of any secondary market will still depend on regulation, eligibility rules, investor participation, market infrastructure, and demand for the underlying asset.

For that reason, the best RWA thesis is not “tokenization makes everything liquid.” It is “tokenization can make historically cumbersome assets more transferable, more interoperable, and easier to administer while preserving the economic reality of the asset underneath.”


The Token Matters Less Than What It Represents

As more stocks, funds, credit products, commodities, real estate interests, and private assets move on-chain, investors will need a more sophisticated framework for comparing them. “RWA” will become too broad a label to say much on its own.

The questions that matter will look increasingly familiar:

  • What exactly does the token represent?
  • What legal rights does the holder have?
  • What produces the underlying cash flow?
  • What are the principal risks to that cash flow?
  • How diversified is the underlying portfolio?
  • What fees, taxes, and deductions apply?
  • How transparent is the reporting?
  • What happens if the tokenization platform, custodian, or service provider changes?

That is healthy. The maturation of RWA investing should move attention away from the novelty of tokenization and toward the quality of the asset and structure being tokenized.


What the next phase of RWA investing looks like

Tokenized stocks are an important milestone because they normalize the idea that conventional financial exposure can live on-chain. They also help regulators, institutions, exchanges, and investors learn how digital ownership can work at scale.

But the most consequential phase may come next. Once the rails are accepted, tokenization can be applied to assets where legacy finance has left more friction in place: private real estate, infrastructure, specialty credit, commodities, energy assets, and other cash-flowing property rights that have traditionally been reserved for institutions, insiders, or investors with large amounts of capital.

That is the opportunity Mineral Vault was designed around. We are not using blockchain to invent a new source of value. We are using it to open a long-established U.S. real-asset market in a more accessible, transparent, and programmable format.

Tokenized stocks show that assets can move on-chain. Tokenized royalties show why some assets may be more valuable once they get there.

Final Thoughts

The RWA market is moving quickly from proof of concept toward a broader question of portfolio construction. Investors will increasingly be able to hold public equities, fixed income, private credit, real estate, commodities, and alternative income assets within the same digital environment.

In that world, the winners will not necessarily be the assets with the most recognizable tickers. They may be the assets where tokenization creates the greatest difference between the old investment experience and the new one.

U.S. mineral royalties are a compelling example. They are backed by real property rights, linked to real energy production, capable of producing recurring cash flow, and historically difficult for most investors to access directly. Tokenization does not change those fundamentals. It makes them easier to reach, easier to administer, and easier to understand.

That is what the next phase of RWA investing should be about: not putting blockchain in front of every existing asset, but using blockchain where it can genuinely widen access to productive real-world value.

Disclaimer: This article is educational in nature and should not be considered investment, tax, or legal advice.
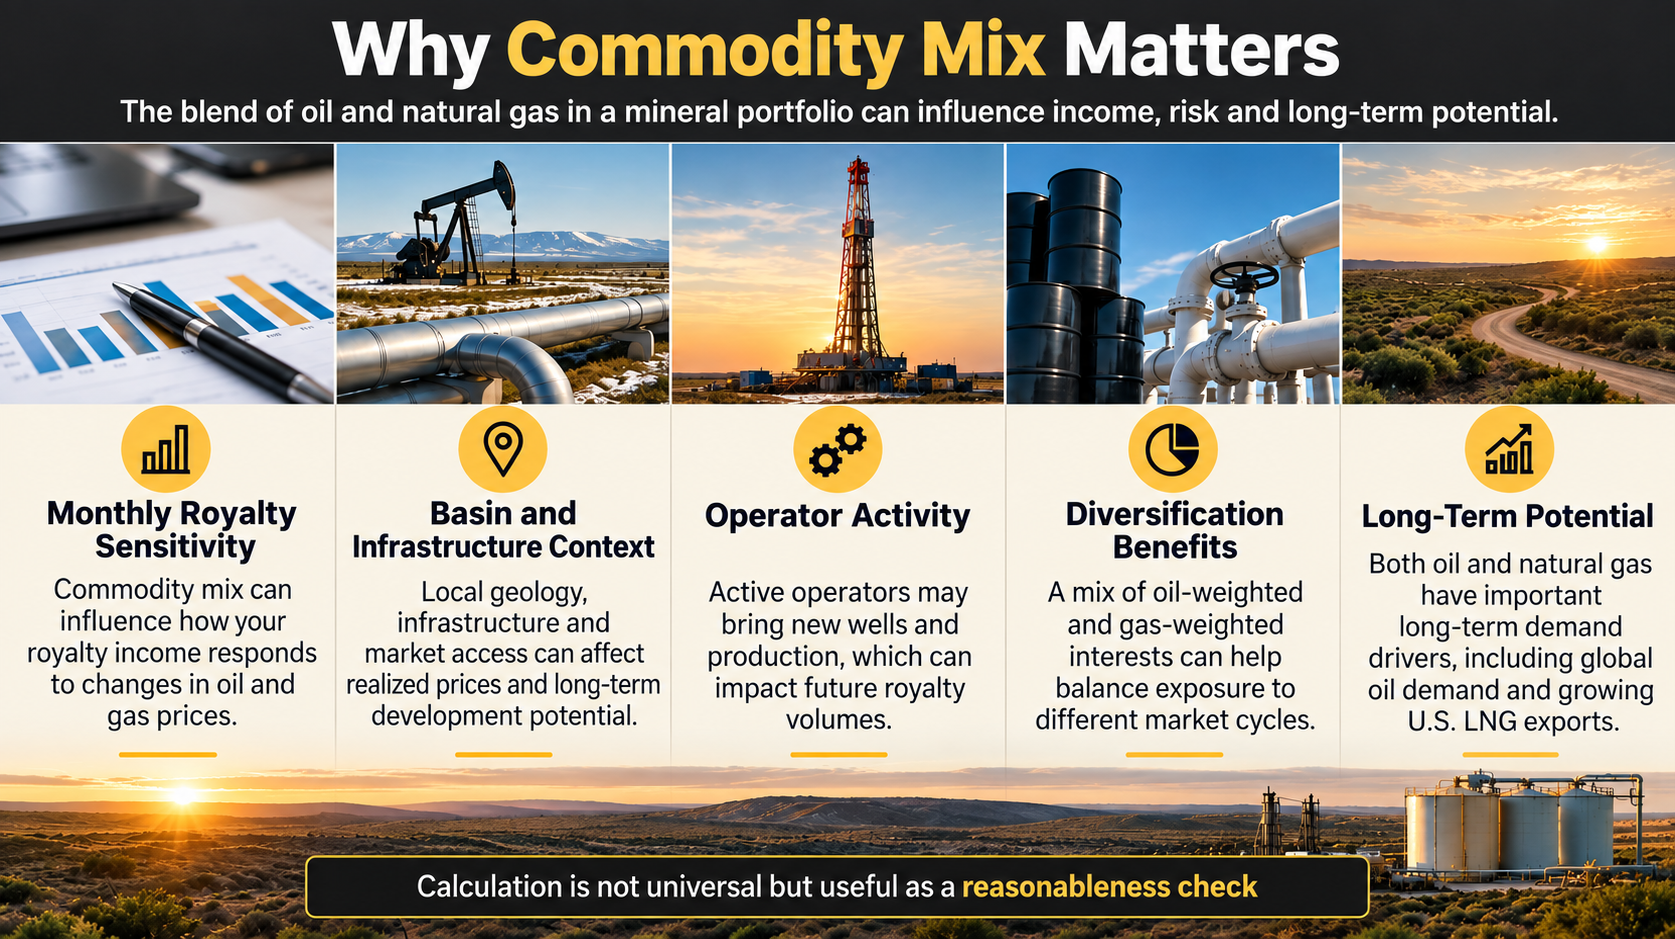
Oil-Weighted vs. Gas-Weighted Mineral Interests: Why Commodity Mix Matters

Most investors understand that oil and natural gas prices fluctuate differently. Fewer understand how that difference affects mineral and royalty interests.

A mineral portfolio is not just “energy exposure.” It can be oil-weighted, gas-weighted, or balanced between multiple revenue streams. That commodity mix can influence monthly royalty income, sensitivity to market cycles, upside from new development, and how the asset behaves inside a broader portfolio.

For investors evaluating mineral and royalty interests, commodity mix is one of the most important details to understand.


What does “oil-weighted” or “gas-weighted” mean?

When people describe a mineral interest as oil-weighted or gas-weighted, they are talking about the revenue mix of the underlying wells or acreage.

An oil-weighted mineral interest receives more of its revenue from crude oil and related liquids.

A gas-weighted mineral interest receives more of its revenue from natural gas production.

Some properties are clearly one or the other. Others produce a mix of crude oil, natural gas, and natural gas liquids. In a diversified mineral portfolio, different parts of the portfolio may have different commodity profiles.

That matters because oil and gas markets do not always move together.


Oil and gas respond to different market forces

Oil is a global commodity. Prices are influenced by worldwide supply and demand, OPEC+ decisions, geopolitical risk, shipping flows, refinery demand, inventories, and macroeconomic expectations.

Natural gas is more regional. In the United States, gas prices are heavily influenced by domestic production, weather, storage levels, pipeline constraints, power demand, industrial demand, and increasingly, LNG export demand.

This difference creates different risk and return patterns.

An oil-weighted royalty position may be more sensitive to global crude price cycles. A gas-weighted royalty position may be more sensitive to U.S. gas fundamentals, seasonal demand, and regional takeaway capacity.

Neither is automatically better. The right question is: what role is the commodity mix playing in the portfolio?


Why oil-weighted minerals can behave differently

Oil-weighted mineral interests are often attractive because crude oil is a globally traded commodity with deep markets and broad demand.

When oil prices rise, oil-weighted royalties can benefit because revenue is tied to the value of produced barrels. If production volumes remain steady and realized prices increase, royalty revenue can improve.

Oil-weighted properties can also be appealing in basins where operators are actively drilling because new wells may bring fresh production onto the acreage.

But oil-weighted exposure also comes with tradeoffs.

Oil prices can be volatile. Global supply decisions, geopolitical events, economic slowdowns, and changes in refinery demand can all affect crude pricing. A month with strong production can still produce weaker revenue if oil prices decline meaningfully.

For mineral owners, the key is not to assume oil exposure is always stronger. It is to understand how much of the portfolio’s royalty income depends on crude prices and how diversified that exposure is across wells, operators, and locations.


Why gas-weighted minerals deserve a closer look

Gas-weighted mineral interests are sometimes misunderstood because U.S. natural gas has historically been more regional and more volatile than oil.

Natural gas demand can shift sharply with weather. Warm winters can pressure prices. Hot summers can increase power demand. Pipeline constraints can create regional price differences. Production growth can temporarily overwhelm demand.

But the U.S. natural gas story is changing.

One of the biggest long-term shifts is the expansion of U.S. LNG exports. LNG allows U.S. natural gas to reach international markets, creating a stronger connection between domestic gas production and global gas demand.

The U.S. Energy Information Administration reported that U.S. LNG exports rose 23% in the first half of 2026 because of higher export capacity. EIA has also forecast that U.S. LNG exports will continue increasing as multiple LNG export projects start operations and ramp up production by the end of 2027.

That does not mean gas-weighted minerals are guaranteed to outperform. It does mean investors should not dismiss natural gas exposure as simply weaker oil exposure. It has its own demand drivers, infrastructure story, and long-term market logic.


Why LNG export expansion matters for gas-weighted royalties

LNG export growth matters because it can create additional demand for U.S. natural gas.

For gas-weighted mineral interests, this is relevant in several ways:

  • Demand support: More LNG export capacity can increase demand for U.S. gas over time
  • Regional effects: Gas-producing basins with access to pipelines and LNG demand centers may benefit more than constrained areas
  • Operator activity: Stronger gas economics can influence where operators choose to drill and complete wells
  • Price sensitivity: Gas-weighted royalties may become more exposed to global gas market conditions as LNG links U.S. supply to international demand

This is not a promise of higher distributions. LNG projects take time, pricing remains cyclical, and natural gas markets can still be oversupplied. But for investors evaluating commodity mix, LNG expansion is an important reason to pay attention to gas exposure rather than treating it as secondary.


Commodity mix affects monthly distributions

Royalty distributions are driven by real production and real market prices. That means commodity mix can influence how monthly income moves.

An oil-weighted month may be affected most by crude prices and oil production volumes. A gas-weighted month may be affected more by Henry Hub prices, regional basis differentials, gas volumes, and seasonal demand.

A balanced portfolio may have multiple sources of movement at once. Oil prices might strengthen while natural gas weakens. Gas volumes might increase while oil production declines. Natural gas liquids may contribute differently than either crude oil or dry gas.

This is why royalty income should not be viewed like a fixed coupon.

A monthly distribution is the output of a real asset system. Commodity mix is one of the reasons that output changes.

Step 1: Identify the revenue source

The first step is simple: understand where the revenue is coming from.

Is the property mainly producing crude oil? Dry natural gas? Natural gas liquids? A mix?

This matters because oil and gas is not one single market. The production stream determines the pricing exposure.

Step 2: Look at basin and infrastructure context

Commodity mix is only part of the story. Location matters too.

A gas-weighted asset in a region with strong takeaway capacity may behave differently from gas production in a constrained basin. An oil-weighted asset in a highly active basin may have different future drilling potential than an isolated property with limited development activity.

For mineral investors, the questions should include:

  • Which basin is this production tied to?
  • Are operators actively developing nearby acreage?
  • Is there pipeline or processing infrastructure available?
  • Is the property exposed to oil, gas, liquids, or all three?

Step 3: Understand operator incentives

Operators make the decisions that turn acreage into production.

If gas prices are weak, some operators may slow drilling in gas-heavy areas. If LNG demand, power demand, or industrial demand improves the outlook, operators may become more willing to develop gas-weighted acreage.

Similarly, oil-weighted development depends on crude economics, service costs, capital discipline, and each operator’s inventory priorities.

Mineral owners are passive, but operator activity still matters.

Step 4: Evaluate diversification

A single oil-weighted or gas-weighted property can be exposed to one commodity, one operator, one basin, and one development plan.

A diversified mineral portfolio can reduce that concentration.

Diversification does not eliminate commodity risk. It can, however, prevent the entire royalty stream from depending on one product, one operator, or one regional market condition.

This is especially important when commodity markets are moving in different directions.


Key Takeaways

  • Oil-weighted minerals tend to be more sensitive to crude oil prices and global oil market dynamics
  • Gas-weighted minerals are more tied to U.S. natural gas fundamentals, weather, storage, infrastructure, and LNG demand
  • U.S. LNG export expansion is an important reason investors should pay closer attention to gas-weighted mineral interests
  • Commodity mix can influence monthly royalty distributions, future drilling potential, and portfolio behavior
  • Neither oil-weighted nor gas-weighted exposure is automatically better; the right answer depends on asset quality, operator activity, diversification, and investor objectives

Where Mineral Vault fits in

Mineral Vault’s approach is built around the idea that mineral and royalty interests should be evaluated as real assets, not generic energy labels.

That means looking at production, operators, geography, title, development potential, revenue mix, expenses, and transparency. Commodity mix is one important part of that process.

Oil-weighted and gas-weighted mineral interests can both play a role in a modern royalty portfolio. The key is understanding what each one contributes and what risks each one introduces.

As U.S. energy production continues to evolve, and as LNG exports create new links between American natural gas and global demand, commodity mix will become even more important for investors evaluating mineral and royalty exposure.


Final thought

Mineral interests are often described broadly as oil and gas assets. But the details matter.

An oil-weighted mineral interest and a gas-weighted mineral interest can behave differently, respond to different market forces, and play different roles in a portfolio. Investors do not need to predict every move in commodity prices, but they do need to understand what their royalty income is tied to.

Commodity mix should not be a footnote for a mineral portfolio. It is one of the most critical considerations when building long-term, sustainable oil & gas asset portfolios.

Disclaimer: This article is for informational purposes only and does not constitute investment, legal, tax, or accounting advice. Mineral and royalty investments involve risk, including commodity price risk, production risk, operator risk, liquidity risk, tax risk, and possible loss of principal. Any investment decision should be made only after reviewing the applicable offering documents and disclosures.

Passive Ownership, Active Operators: Why Operator Quality Matters in Mineral Investing

One of the most appealing features of mineral and royalty ownership is its passive structure. The mineral owner does not run drilling rigs, hire field crews, build gathering systems, or manage day-to-day well operations. When production occurs, the operator generally carries the operational burden while the mineral or royalty owner receives an agreed share of production revenue.

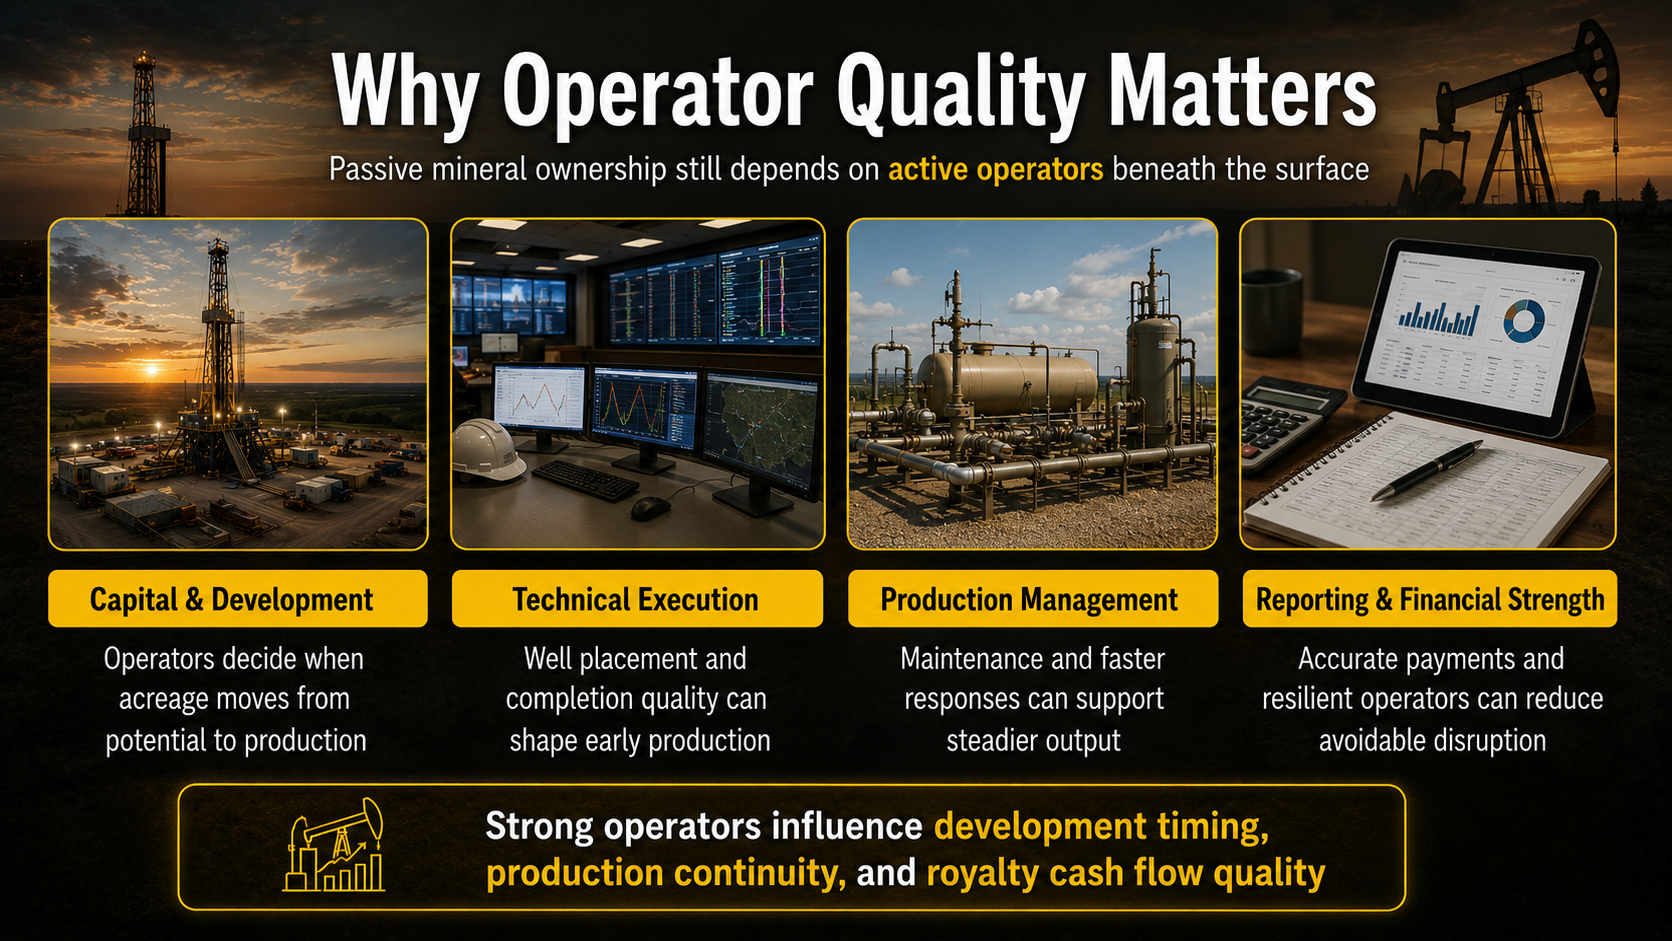
But passive ownership does not mean the underlying asset is passive. Every producing well is being managed by an active exploration and production company. That operator decides when to drill, how to complete a well, how aggressively to maintain production, when to repair or shut in equipment, and how to allocate capital across its inventory. Those choices can influence the timing, durability, and quality of royalty cash flow.

This is why operator quality matters in mineral investing. Mineral owners may not be writing drilling checks, but they are still economically connected to the companies making the operating decisions.

Key idea: Mineral ownership can be passive for the investor while remaining operationally intensive beneath the surface. The quality of the operator is one of the links between the property right and the cash flow it ultimately produces.


The mineral owner and the operator play very different roles

A mineral interest is a real property right in the subsurface estate. When that acreage is leased, an operator receives the right to explore for and produce hydrocarbons under the terms of the lease. In exchange, the mineral owner may receive a lease bonus and an ongoing royalty tied to production.

That division of responsibilities is fundamental. The operator supplies the technical expertise, capital, personnel, equipment, and infrastructure required to develop the resource. The mineral owner participates economically without taking on the same routine drilling and operating obligations associated with a working interest.

This structure is one reason mineral royalties can serve as an attractive form of real-asset income. It is also why the identity and quality of the operator deserve careful attention. The mineral owner is passive, but the operator is not interchangeable. Two companies can hold leases in similar geology and still produce different outcomes because of differences in capital strength, technical execution, operating discipline, infrastructure access, and development strategy.


Operator quality begins with capital allocation

Undeveloped acreage does not create royalty income simply because hydrocarbons may be present. An operator must choose to commit capital, obtain permits, drill the well, complete it, connect it to infrastructure, and place it into production. The timing of those decisions is rarely automatic.

Operators continually rank drilling opportunities against the rest of their inventory. Commodity prices matter, but so do expected well economics, service costs, available crews, pipeline capacity, corporate debt levels, and broader capital-allocation priorities. A well may be technically attractive and still remain undeveloped if the operator has stronger opportunities elsewhere or lacks the financial flexibility to move forward.

For a mineral owner, this means operator quality is partly about whether the company has both the ability and the willingness to develop the acreage responsibly. A well-capitalized operator with a strong inventory position may be better equipped to maintain a consistent development program through changing market conditions. A financially constrained operator may delay completions, reduce activity, sell assets, or focus only on the most immediate needs.

This is especially important when evaluating future drilling potential. Undeveloped acreage can provide meaningful upside, but that potential becomes cash flow only when a capable operator converts it into producing wells.


Drilling and completion quality affect the production profile

Bringing a well online is not a standardized manufacturing process. Geological interpretation, well placement, lateral length, completion design, spacing, equipment selection, and field execution can all affect how a new well performs. Even within the same basin, operators can achieve different results from comparable acreage.

The U.S. Energy Information Administration has repeatedly documented that drilling efficiency and new-well productivity are major drivers of U.S. production. Operators have improved output through longer laterals, optimized completion designs, multi-well development, and more efficient use of crews and equipment. Those improvements do not remove geological risk, but they show how technical and operational capability can influence the value created from an acreage position.

For royalty owners, better execution can mean stronger initial production, a more efficient path from drilling to first sales, and a more productive use of the underlying resource. Poor execution can mean delays, cost pressure for the operator, underperforming wells, or development plans that fail to capture the acreage’s full potential.

The royalty owner may not pay the drilling bill, but the quality of that drilling still matters.


Good operators manage existing production, not just new wells

Operator quality is often discussed only in the context of drilling. Yet most royalty income in a producing portfolio comes from wells that are already online. Managing those wells well can be just as important as drilling the next one.

Producing assets require monitoring, maintenance, repairs, pressure management, artificial-lift optimization, gathering coordination, and responses to weather or equipment failures. Wells may be temporarily shut in because of mechanical issues, pipeline constraints, maintenance, or market conditions. How quickly and effectively an operator responds can affect production continuity.

No operator can eliminate downtime or natural decline. The question is whether the company has the systems, field presence, technical staff, and financial resources to manage those realities responsibly. Strong operators tend to treat production optimization as an ongoing process rather than simply drilling a well and moving on.

For the mineral owner, that discipline can show up in steadier production, faster recovery from interruptions, and a more durable stream of royalty revenue over time.


Reporting and payment discipline are part of operator quality

Royalty income depends not only on what is produced, but also on how accurately and promptly that production is measured, reported, allocated, and paid. Operators and purchasers must track volumes, product types, ownership decimals, sales values, deductions, and production months across large numbers of wells and interest owners.

That process is complex, and timing differences are normal. Government production datasets themselves can be revised when operators report late or when allocations change. For private royalty owners, delayed statements, suspense balances, ownership changes, or accounting corrections can affect when revenue appears even if the underlying well continued to produce.

A quality operator maintains strong revenue-accounting systems, responds to ownership documentation, handles division orders carefully, and communicates when issues arise. That does not guarantee perfectly uniform payments, but it reduces avoidable friction between production at the wellhead and cash reaching the owner.

This is one reason a royalty distribution can vary month to month without signaling a fundamental problem. Sometimes the cause is commodity pricing or production. Sometimes it is simply the timing of operator reporting and remittance. Understanding the operator base helps investors interpret those movements more intelligently.


Financial strength matters through commodity cycles

Oil and gas development is capital intensive. Operators fund drilling programs, field operations, infrastructure commitments, regulatory compliance, and eventual plugging and reclamation obligations. Their capacity to meet those obligations can change as commodity prices, service costs, interest rates, and capital markets move.

A financially resilient operator may be better positioned to continue maintenance and selected development during a downturn. A weaker operator may cut activity sharply, defer work, sell properties, or in severe cases enter bankruptcy. The existence of state and federal orphan-well programs is a reminder that operator responsibility continues long after first production and that financial capacity is not merely an abstract corporate metric.

For mineral investors, this does not mean only the largest companies are acceptable. Many private and independent operators have deep basin expertise, disciplined balance sheets, and excellent execution records. It means operator evaluation should consider financial durability alongside geology and current production.


Regulatory and environmental performance cannot be separated from economics

Operators are responsible for complying with permits, production-measurement rules, safety requirements, environmental standards, plugging obligations, and site-reclamation requirements. Regulators inspect operations and can issue notices, penalties, or orders when operators fail to comply.

For a passive mineral owner, those responsibilities may feel distant, but poor compliance can still affect the asset. Regulatory problems can delay development, interrupt production, create disputes, or make a property less attractive to future buyers and operators. Strong compliance practices support the long-term integrity of the acreage and reduce the risk that preventable operating failures interfere with production.

Responsible operation is therefore not separate from investment quality. It’s part of it.


Operator size is not the same as operator quality

It is tempting to reduce operator analysis to a familiar-name test. Large public companies often bring substantial capital, sophisticated engineering teams, established systems, and access to infrastructure. Those are meaningful advantages, but size alone does not answer every question.

A smaller operator may have sharper local knowledge, a concentrated position in one basin, lower overhead, or a stronger incentive to develop a particular set of properties. A large operator may control excellent acreage but rank it below other projects in its global portfolio. A private operator may move quickly, while another may be financially stretched. A public company may have strong resources, while its development cadence shifts with shareholder-return priorities.

The better questions are more specific: Does the operator have a proven record in the basin? Is it financially capable? Does it drill and complete wells efficiently? Does it maintain existing production? Is it developing the acreage at a rational pace? Does it report and pay accurately? Does it operate responsibly?

Operator quality is a collection of behaviors and capabilities, not a logo.


Why operator diversification matters

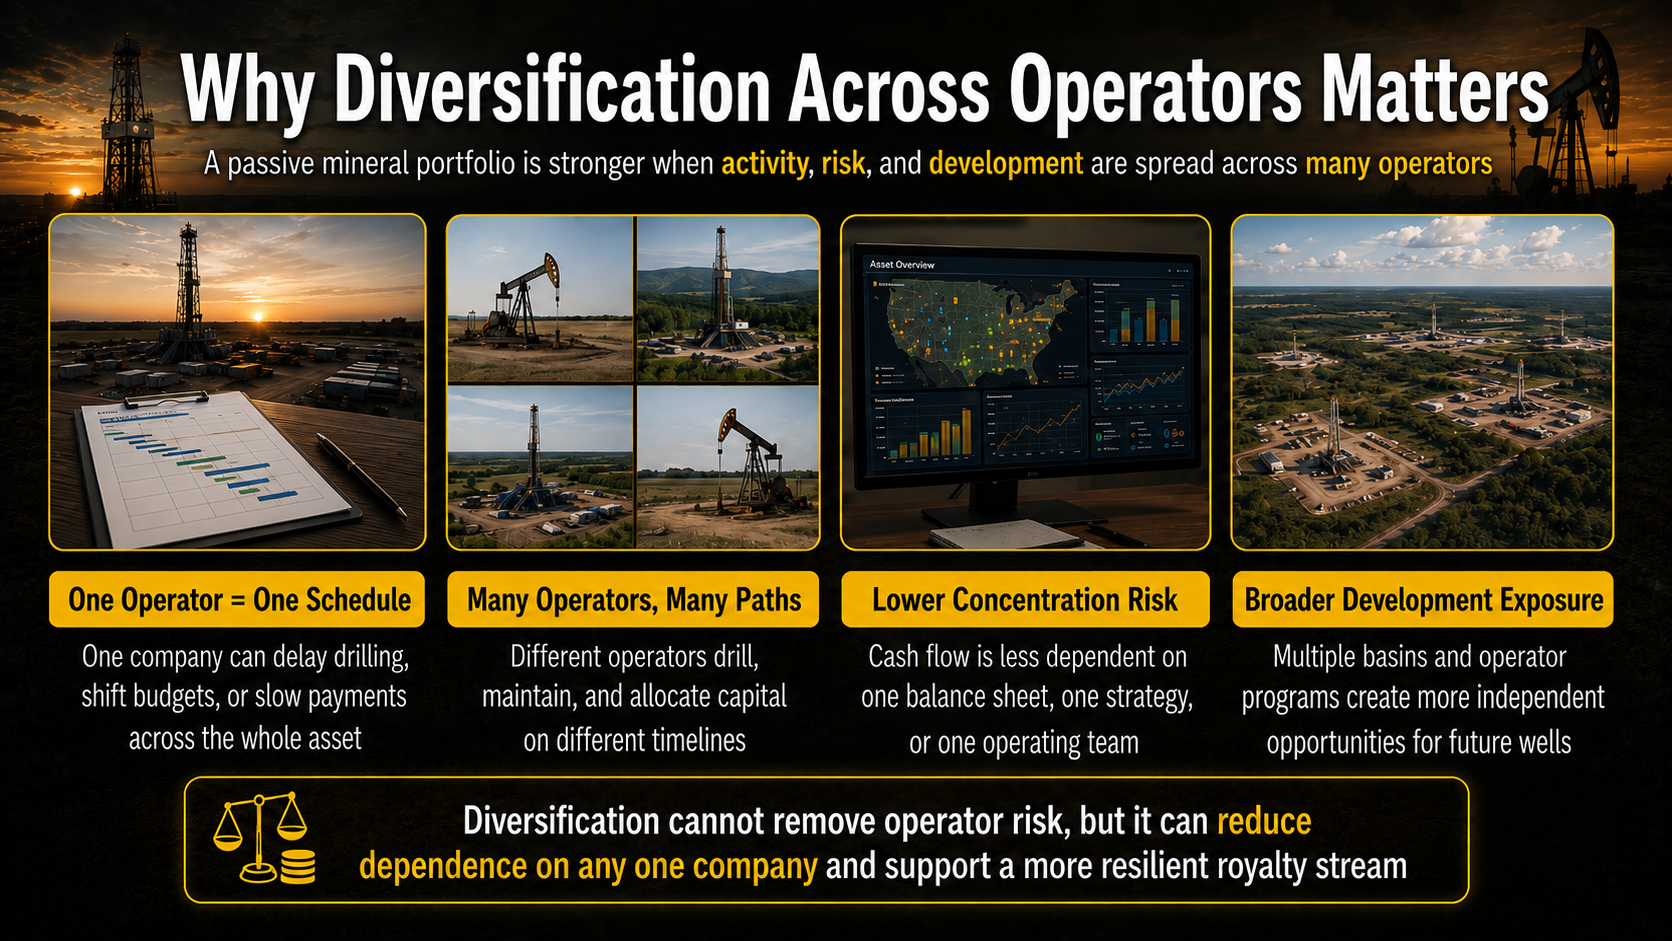
Even a high-quality operator can change its budget, sell assets, experience delays, or shift its priorities. That is why operator quality and operator diversification should be considered together.

A portfolio tied to one operator is exposed to that company’s development calendar, balance sheet, operational decisions, and reporting systems. If the operator slows activity or encounters problems, the effects can be felt across the entire asset base. A portfolio spread across many operators is less dependent on any single corporate decision.

Mineral Vault I is tied to more than 2,500 producing wells, more than 10,000 gross acres, over 150 operators, and 9 U.S. states. That operator breadth is important for two reasons. First, it reduces concentration risk. Second, it creates multiple independent paths for future development. Different operators allocate capital on different schedules, work in different basins, and respond differently to market conditions. Activity may slow in one part of the portfolio while continuing elsewhere.

Diversification does not make every operator equal and does not remove operating risk. It prevents the entire royalty stream from resting on the quality or decisions of one company.


How operator quality fits into Mineral Vault’s property selection

Mineral Vault I was assembled through more than 350 individual transactions across a broad set of producing properties. The evaluation process did not focus only on current revenue or the number of existing wells. It also considered basin geography, future development potential, property concentration, and the quality of the operators responsible for turning subsurface resources into production.

Emphasis was placed on established exploration and production companies with demonstrated operating track records. At the same time, the portfolio was intentionally diversified across more than 150 operators so that no single company would define the entire outcome.

That combination is important. Current production shows that an asset is already generating revenue. Future drilling potential creates the possibility of reserve replacement as older wells decline. Operator quality helps determine how effectively and when that future potential may be developed. Operator diversification reduces dependence on any one development plan.

In other words, good mineral underwriting is not simply a search for acreage. It is an assessment of the property, the production, the development runway, and the companies responsible for operating the wells.


How operator decisions appear in monthly royalty distributions

Operator quality is not always visible in a single monthly payment. Commodity prices can rise or fall. Wells can experience temporary downtime. Payments can shift between reporting periods. One operator may bring a new well online while another completes maintenance or delays a remittance.

Over time, however, operator behavior becomes part of the portfolio’s cash-flow pattern. Development activity can add new production. Effective maintenance can preserve output from mature wells. Efficient completions can improve the economics of new wells. Accurate reporting and timely remittance can reduce accounting noise. Financial strength can support continuity through weaker markets.

This is why investors should not evaluate a royalty portfolio by looking only at a headline well count or one month of distributions. The more useful questions are how the operator base is composed, how concentrated it is, how active those operators are, and whether the acreage has credible development potential under their stewardship.


Passive ownership works because active operators do the work

The passive nature of mineral ownership is not a contradiction. It is the result of a division of labor. The mineral owner supplies the property right. The operator supplies the capital, expertise, infrastructure, and day-to-day execution required to produce the resource.

When that relationship works well, mineral owners can participate in production revenue without becoming oil and gas operators themselves. But the quality of the active party still matters to the passive party. A royalty interest does not operate the well, yet its value is connected to how that well and the surrounding acreage are developed and managed.

Tokenization can make ownership easier to access, track, and transfer. It can make distributions and supporting documentation more transparent. It does not replace the importance of the underlying operators. The quality of a tokenized real-world asset still begins with the quality of the real-world activity beneath it.


Key takeaways

  • Mineral and royalty owners can receive production-linked income without directly operating wells or funding the same routine drilling costs associated with working interests.
  • Operator quality matters because operators control development timing, drilling and completion execution, maintenance, production continuity, reporting, compliance, and long-term asset stewardship.
  • Financial strength is important, but operator size alone is not a complete measure of quality. Basin expertise, execution history, reporting discipline, and responsible operations also matter.
  • Operator diversification reduces dependence on a single company’s budget, strategy, balance sheet, and development calendar.
  • Mineral Vault I combines exposure to more than 150 operators with more than 2,500 producing wells across 9 states, helping create a broader and less concentrated royalty base.
  • Tokenization modernizes access and administration, but the economics still depend on real properties managed by real operators.

Final thought

Mineral investing is often described as passive, and from the owner’s perspective, that description is largely accurate. The owner does not need to operate rigs, manage crews, or make daily field decisions.

But every royalty check begins with an active operator making hundreds of decisions beneath the surface and across the field. The best mineral portfolios recognize that reality. They seek quality operators, diversify across many of them, and pair current production with credible future development potential.

Passive ownership is most powerful when the active operators behind it are capable, disciplined, and diversified.

Disclaimer: This article is educational in nature and should not be considered investment, tax, or legal advice. Target outcomes and future development are not guaranteed, and mineral and royalty investments remain subject to commodity, production, operator, legal, tax, liquidity, and other risks.
Why Mineral Interests Are One of the Most Misunderstood Asset Classes in America

Most investors can explain what a bond is in one sentence. They can usually describe a dividend stock, a REIT, or even a commodity ETF without much trouble. Mineral interests are different. Even though they are tied to real property, real production, and real cash flow, they are still one of the most misunderstood asset classes in America.

That confusion does not exist because mineral interests are unimportant. It exists because they sit at the intersection of real estate, energy, private markets, and legal title, yet they do not behave exactly like any of those categories. For decades, that made them hard to access, hard to compare, and easy to mislabel.

At Mineral Vault, we believe this confusion has caused many investors to overlook an asset class that deserves a much closer look. Once mineral interests are understood on their own terms, the picture becomes much clearer: they are not direct drilling deals, they are not fixed income, and they are not just another form of public-market energy exposure. They are a distinct form of real-asset ownership with a return profile that many investors have rarely had a fair chance to evaluate.


Why the confusion starts so early

Most people first hear about oil and gas investing through the wrong lens. They think about drilling risk, wildcat wells, giant capital budgets, or public energy stocks that rise and fall with commodity headlines. Mineral interests are often grouped into that same mental bucket, even though the economics can be very different.

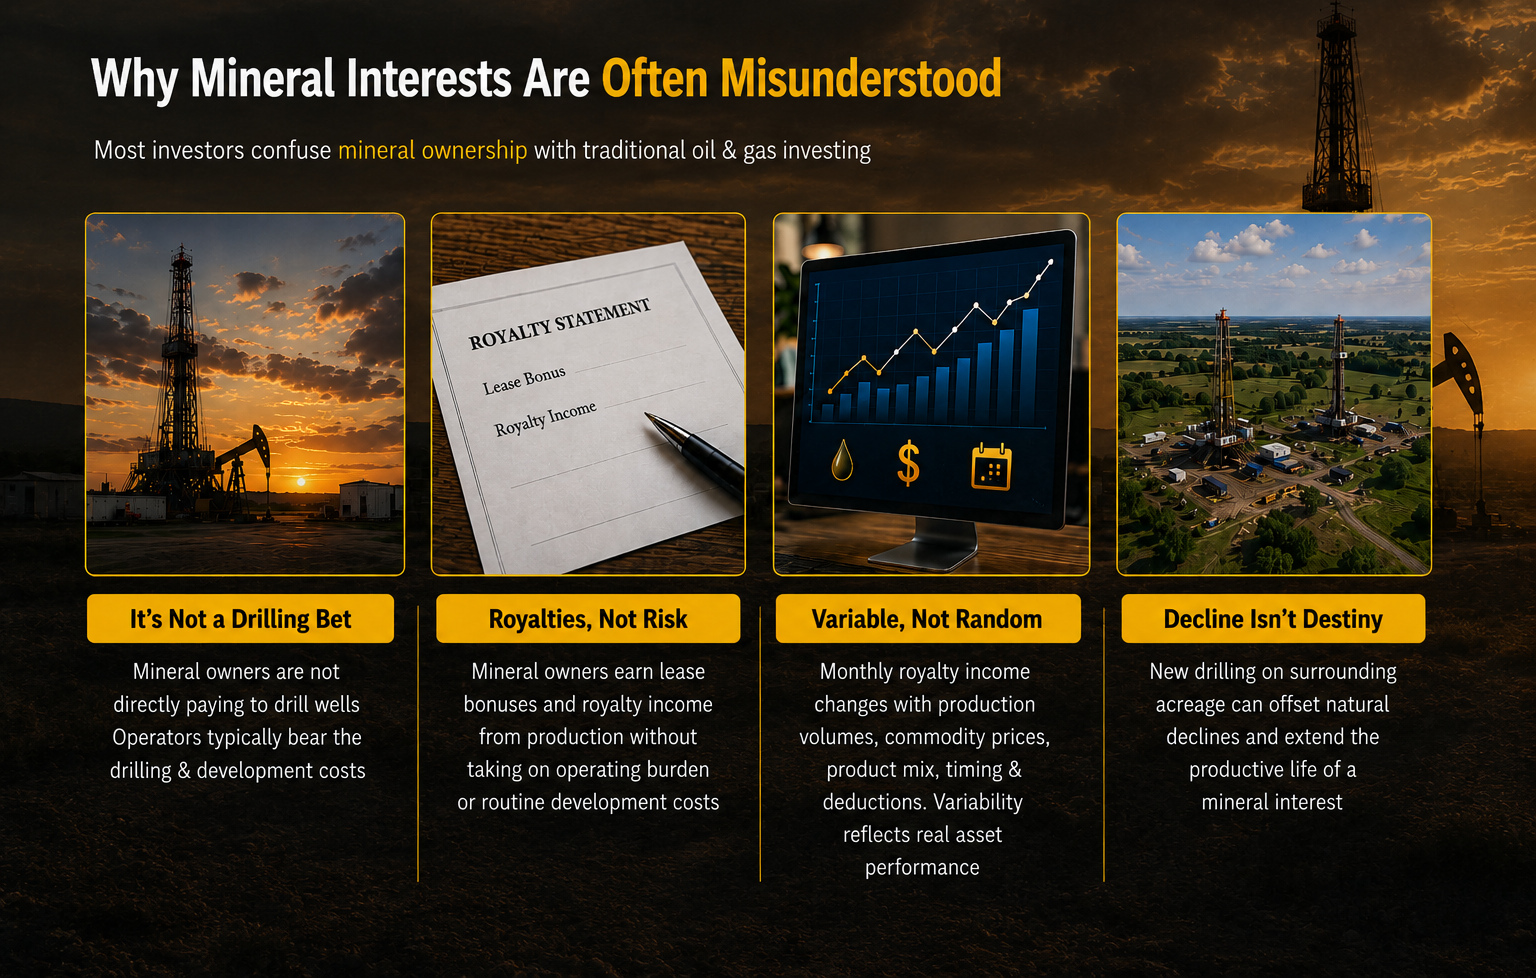
A mineral interest is a real property right. When the underlying acreage is leased and production occurs, the mineral owner can receive lease bonuses and royalty income from the operator’s extraction activity. That is a very different position from being the company paying to drill the well. In many cases, the mineral owner benefits from production without taking on the same operating burden or routine development costs that come with a working interest.

That distinction matters, but it is easy to miss. The words used in the industry — minerals, royalties, overriding royalties, working interests, net revenue interests, term assignments, division orders — are not intuitive to most investors. When the vocabulary is unfamiliar, the whole asset class can look more exotic and opaque than it really is.


Mineral interests are real property, but they do not look like traditional real estate

Another reason mineral interests are so misunderstood is that they are a form of real estate that most people never physically see. A house, warehouse, apartment building, or office property is easy to visualize. Mineral interests are different because the economic value sits below the surface.

That can make them feel abstract, even though the legal foundation is concrete. Mineral interests are ownership rights in the subsurface estate. Their value comes from the natural resources that may be extracted from that acreage, and their cash flow comes from production and lease activity rather than from rent checks or tenant demand.

This is one reason mineral interests are often misclassified. They share some traits with real estate, but they do not behave like plain commercial property. They share some traits with commodity exposure, but they are not simply a bet on spot prices. They can generate income, but they are not a bond. Investors looking for a familiar legacy bucket often end up forcing mineral interests into the wrong one.


Many investors confuse mineral interests with direct drilling exposure

This is probably the biggest misunderstanding of all. When people hear “oil and gas,” they often assume the investment must be cost-heavy, operationally messy, and exposed to the full burden of drilling and development. That assumption can be true for certain energy investments, but it is not the default reality for mineral and royalty ownership.

Mineral Vault’s public materials make this distinction clear. In general, the mineral and royalty interests associated with its offerings are not cost-bearing in the same way working interests are. The operator usually bears the majority of drilling and development costs, while the owner of the mineral interest receives lease bonuses and royalty payments tied to production. That does not mean the investment is cost-free in every possible sense — property taxes, withholding tax effects, management fees, and minor entity-level costs still matter — but it does mean the economics are often very different from what many investors imagine when they think about oilfield risk.

When mineral interests are incorrectly treated as if they were direct participation in drilling programs, investors can overestimate some risks while completely missing other characteristics that actually define the asset class: passive exposure, real-asset linkage, portfolio diversification, and cash flow that comes from production rather than from operating a business.


The cash flow is variable, but it is not arbitrary

Mineral interests are also misunderstood because their income does not behave like a fixed coupon. Some investors see variable monthly distributions and assume the asset is unreliable. In reality, the variability is usually the natural result of how the underlying properties work.

Royalty income can move from month to month because of production volumes, oil and gas prices, product mix, maintenance, downtime, timing differences in operator reporting, and changes in deductions such as property taxes or withholding. That variability is real, but it is not random. It reflects the performance of real producing assets.

Mineral Vault’s structure is designed to make those mechanics easier to follow. Revenue flows from the source entity to the tokenized SPV, monthly distributions are made to token holders, and supporting documentation is published through the transparency page, including dividend reports, spreadsheets, and underlying support for line items. That kind of reporting helps investors understand what changed and why, rather than simply seeing a payout number with no context.

In other words, the misunderstanding is not just about the asset itself. It is also about visibility. When investors cannot easily see what is driving a distribution, they may assume the cash flow is unpredictable by nature. Better reporting does not remove variability, but it does make the cash-flow logic much more intelligible.


Depletion is real, but that is not the whole story

Another reason mineral interests are misunderstood is that the conversation usually stops at depletion. People hear that oil and gas wells decline over time and conclude that the whole category must simply be a shrinking stream of income. Depletion is absolutely real, and investors should understand that clearly. Mineral Vault itself says production volumes and cash flows are likely to decline over the 15-year term of a tokenized offering as depletion takes place.

But that is not the whole story, especially in a large, diversified portfolio. Mineral Vault also emphasizes future drilling potential and acknowledges that operators may drill new wells on tokenized properties, creating new production streams that can offset some of the decline from older wells. This is the reserve replacement dynamic.

That matters because a diversified portfolio does not behave like a single-well bet. Some wells are older. Some are newer. Some operators are more active than others. Some acreage is already productive, while some surrounding acreage may still support additional development later on. When reserve replacement occurs across a portfolio of this scale, the overall decline profile can be softer than what an investor might expect if they are thinking only in terms of one well depleting in isolation.

Reserve replacement does not eliminate depletion, and it should never be described that way. What it can do is make the aggregate portfolio behave differently from the simple mental model many people bring to the category. That nuance is one of the most important things modern investors need to understand about mineral interests.


The asset class has historically been buried under paperwork and private-market friction

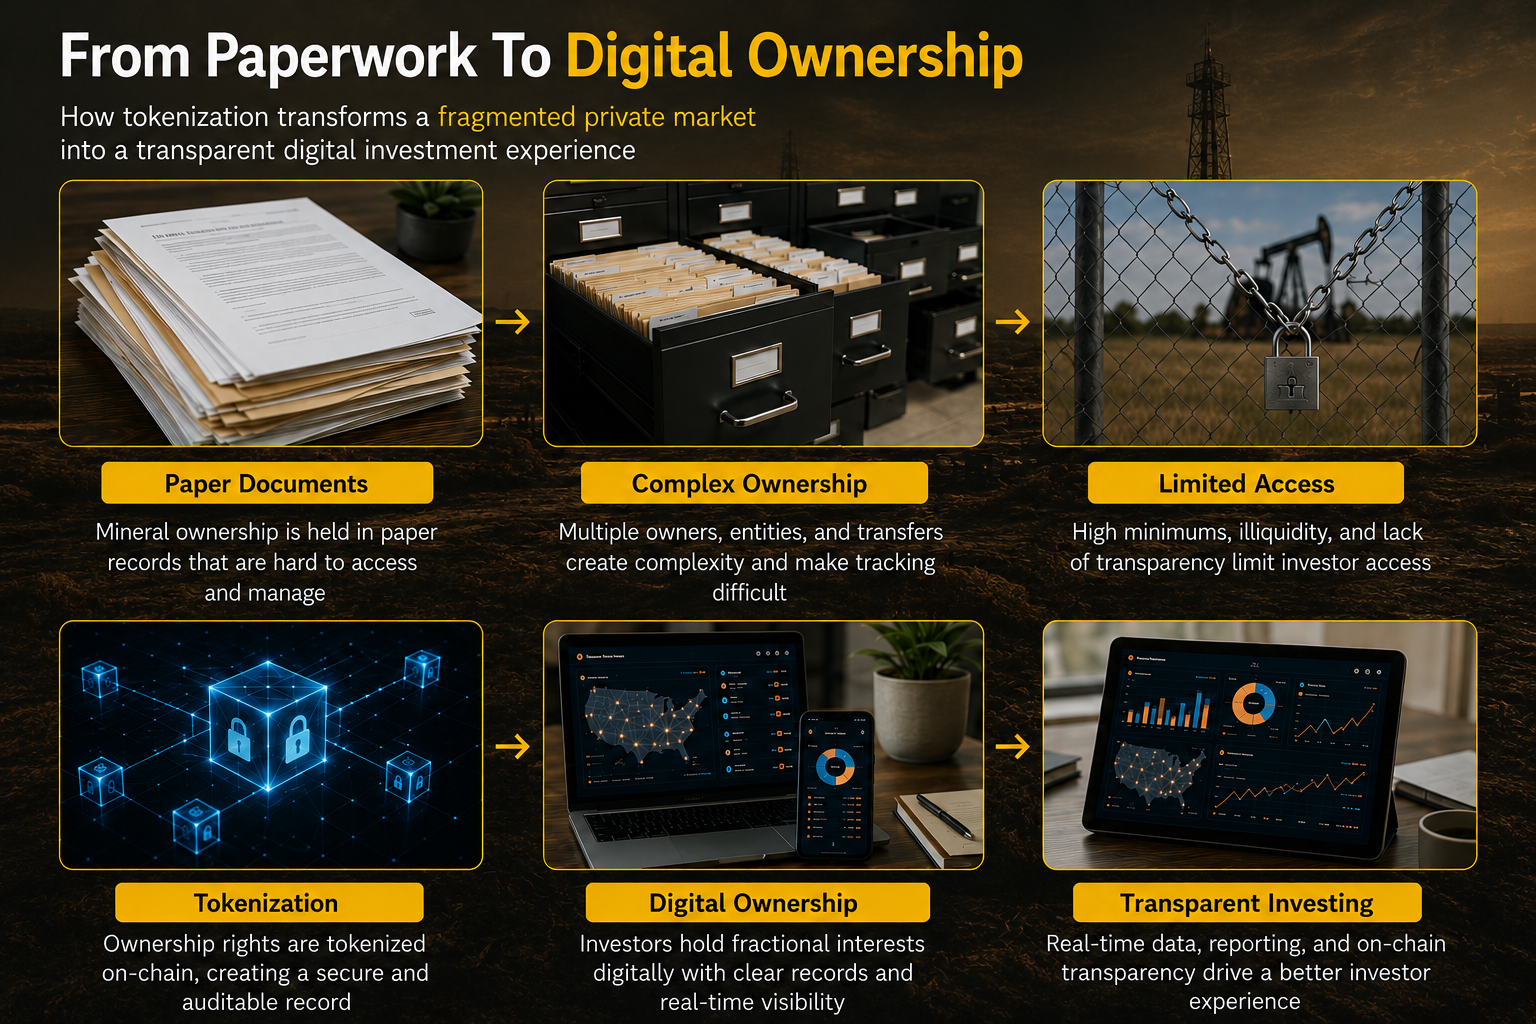
A big part of the misunderstanding is not conceptual at all. It is operational. For decades, mineral interests have been difficult to buy, difficult to diligence, difficult to transfer, and difficult to monitor. That has kept the asset class mostly inside specialist circles.

Traditional ownership often involves fragmented documentation, title complexity, private negotiations, paper-heavy transfer processes, and large capital commitments. Even when the economics are attractive, the ownership experience has rarely felt modern. That creates a strange problem: a real asset with real value ends up looking obscure simply because the infrastructure around it has been outdated and inaccessible.

Mineral Vault was built to change that experience. Its platform uses a tokenized SPV structure to package financial exposure to a diversified set of U.S. mineral and royalty interests into a format designed to be easier to own, easier to transfer, and easier to track. Monthly digital distributions, on-chain ownership records, and public transparency materials do not change the underlying geology, but they do change how investors can engage with the asset class.


Why mineral interests deserve a more accurate place in portfolio conversations

Because the category is so often misunderstood, it is often left out of modern portfolio discussions altogether. Investors usually default to familiar income buckets: bonds for contractual cash flow, dividend stocks for corporate payout growth, and REITs for listed real-estate exposure. Mineral interests do not fit neatly into any one of those categories.

They are best understood as a distinct real-asset income allocation. They can provide exposure to U.S. energy production cash flows, inflation-linked revenue dynamics, and upside from future development, all without requiring the investor to operate wells or fund large drilling budgets directly. At the same time, they come with their own tradeoffs: commodity sensitivity, legal and tax complexity, depletion over time, and a return profile that does not map perfectly onto legacy public-market products.

That is exactly why a better framework matters. If investors mistake mineral interests for bonds, they will misunderstand the variable nature of the cash flow. If they mistake them for direct drilling programs, they will misunderstand the cost structure. If they mistake them for plain real estate, they will misunderstand the revenue drivers. And if they treat them as just another energy stock proxy, they will miss the property-rights foundation that makes them different in the first place.


Where Mineral Vault changes the picture

Mineral Vault’s role is not to pretend this asset class is simple just because it is now tokenized. The point is to make a historically difficult asset class more legible, more accessible, and more transparent.

The platform’s current public materials describe Mineral Vault I as a tokenized vehicle backed by cash-flowing U.S. mineral properties, with monthly USDC distributions, published dividend support, and a structure in which revenue flows into an SPV and then out to token holders after applicable expenses. The properties are selected for current cash flow, future drilling potential, and diversification across location, operator, well type, and resources produced.

That matters because one of the best ways to reduce misunderstanding is to let investors see the asset class more clearly. Better structure, better reporting, and better access do not remove every risk. They do, however, remove some of the old barriers that made mineral interests feel invisible or reserved only for insiders.


Key takeaways

  • Mineral interests are often misunderstood because they sit between multiple familiar asset categories without fitting perfectly into any of them.
  • They are real property rights, not just generic commodity exposure and not the same thing as direct drilling participation.
  • Their cash flow is variable because it is tied to real production and real market conditions, not because it is arbitrary.
  • Depletion matters, but in diversified portfolios, reserve replacement and future drilling potential can materially change how the overall asset behaves over time.
  • Historically, private-market friction and paper-heavy ownership structures helped keep the asset class obscure.
  • Tokenization, transparency, and digital distributions can make mineral interests easier to understand, monitor, and evaluate in a modern portfolio context.

Final thought

Mineral interests are not misunderstood because they are weak. They are misunderstood because they have spent too long living outside the frameworks most investors use every day. They do not trade like common stocks, they do not pay like bonds, and they do not look like surface real estate. That difference has often been treated as a reason to ignore them. We think it is a reason to understand them better.

For investors seeking real-asset exposure, passive income tied to productive U.S. properties, and a return profile that does not simply mimic the usual public-market categories, mineral interests deserve much more serious attention than they typically receive.

Disclaimer: This article is educational in nature and should not be considered investment, tax, or legal advice.
What Actually Determines a Royalty Distribution Month to Month?

A common mistake in income investing is to assume that every monthly payout should behave like a fixed coupon. That is not how mineral royalties work. A royalty distribution is not manufactured in a spreadsheet and pushed outward on a schedule regardless of market conditions. It begins with real oil and natural gas production, real purchaser payments, and real operating activity across the underlying property portfolio.

That is exactly why mineral royalty income can be so compelling. The cash flow is tied to producing assets, but the amount distributed in any given month will move with what the assets actually did. Some months are stronger. Some are softer. The important point is that the changes are usually explainable. They are variable, but they are not random.

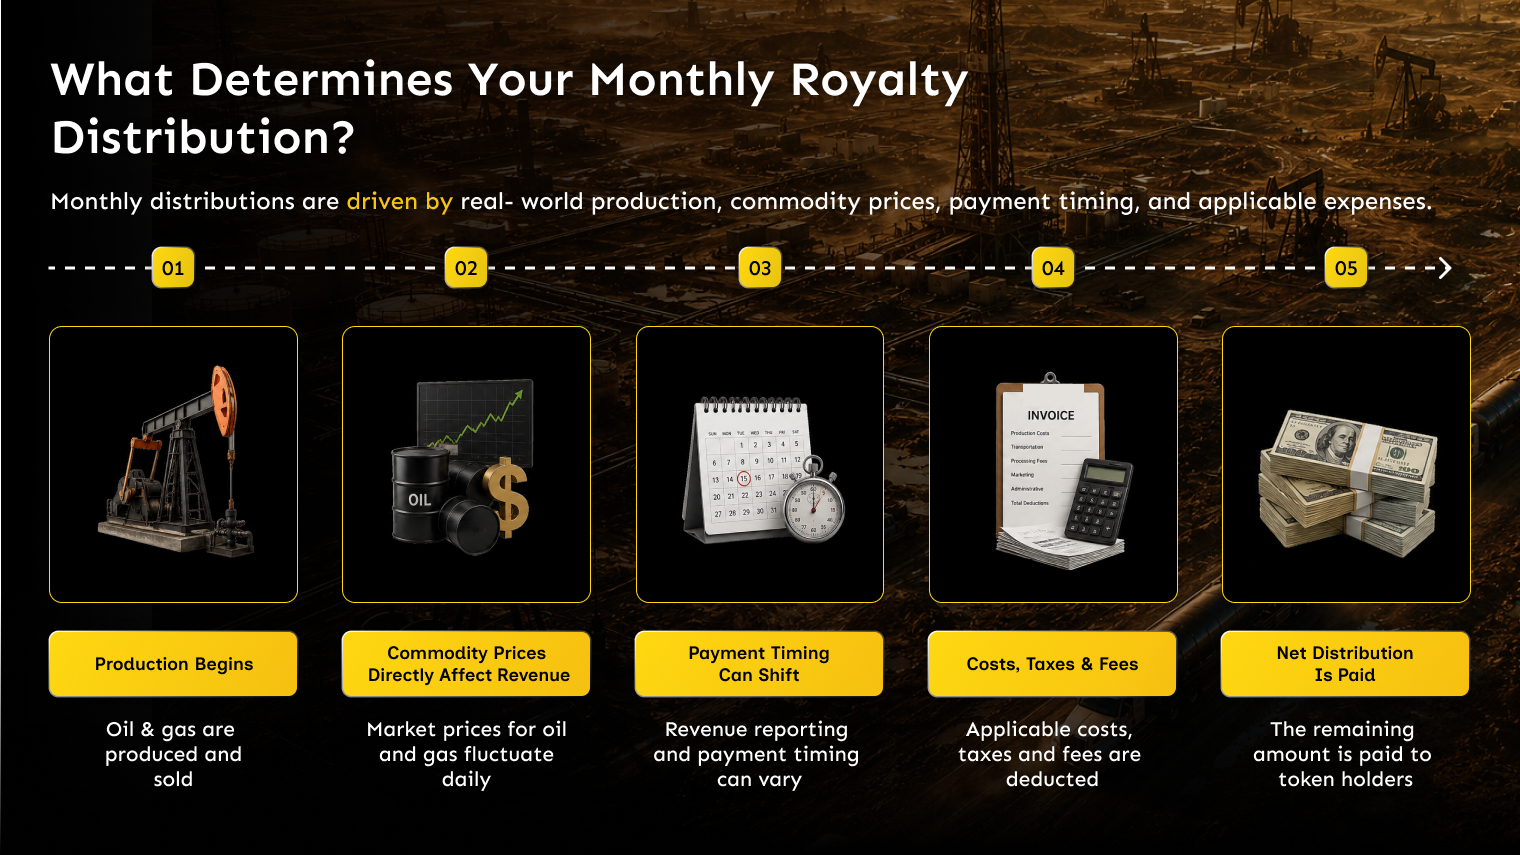
For Mineral Vault I, the right way to think about a monthly royalty distribution is as the end result of a chain: hydrocarbons are produced and sold, revenue is collected, eligible expenses and fees are accounted for, and the remaining distributable amount is paid to token holders in USDC. Once investors understand the moving parts inside that chain, month-to-month changes become much easier to interpret.


It Starts With Production and Sale

Every royalty distribution begins at the wellhead. Mineral Vault I holds royalty exposure across more than 2,500 producing wells, 9 U.S. states, more than 150 operators, and over 10,000 gross acres. Those wells generate revenue only when crude oil, natural gas, and natural gas liquids are actually produced and sold. No production means no revenue. Higher production generally means more revenue. Lower production generally means less.

That sounds simple, but the implications matter. A royalty distribution is fundamentally different from a bond coupon because it is tied to operating assets. Wells do not produce the exact same amount every month. Some decline naturally. Some are temporarily offline for maintenance. Some are constrained by weather, takeaway capacity, or routine field work. Some may outperform expectations. In a large portfolio, all of those moving pieces are happening at once.

This is why one month should never be viewed in isolation. A single distribution is only a snapshot of how the portfolio performed during that collection period. The better question is always: what changed in the underlying production base?


Commodity Prices Directly Affect Gross Revenue

Production volumes are only half of the equation. The same barrels and the same gas volumes can generate materially different revenue from one month to the next if commodity prices move. Mineral Vault’s assets are sold at or near commodity spot prices at month-end, which means realized revenue naturally reflects the pricing environment rather than a fixed contract-like payment stream.

When oil prices rise, royalty revenue can rise even if production is relatively stable. When natural gas prices weaken, revenue can fall even if wells are still producing. Product mix matters as well. A portfolio that receives revenue from crude oil, natural gas, natural gas liquids, and occasional lease bonuses will not move in exactly the same way every month because those revenue streams do not always move together.

That variability is not a flaw in the model. It is part of what gives mineral interests their real-asset character. The distributions are connected to actual energy production and market pricing rather than to a fixed promise detached from the assets themselves.


Timing Matters More Than Many Investors Expect

Even when commodity prices and production are understood correctly, the month in which cash is actually received can still shift. Operators and purchasers do not always remit proceeds on a perfectly uniform timeline. Statements can arrive on different schedules. Certain wells may have short-term payment timing differences. Adjustments can also be booked after the fact.

That means a monthly distribution can sometimes reflect timing as much as economics. In other words, a softer month does not always mean the asset base itself became weaker. It can simply mean that part of the revenue cycle landed in the following distribution period instead of the current one.

This is one of the reasons transparency matters so much in royalty investing. Without visibility into the revenue and expense trail, investors may misread normal timing noise as a fundamental change. With clear reporting, the difference becomes much easier to understand.


The Net Distribution Is Calculated After Real Costs and Fees

Gross revenue is not the same thing as distributable revenue. Once royalty income is received, the tokenized SPV accounts for the costs that actually apply to the portfolio. Mineral Vault has been very clear that these costs are payable from revenue received by the SPV itself, not through future capital calls to token holders.

The largest recurring items include property taxes, minor expenses on revenue, and management fees. Property taxes on producing U.S. oil and gas properties are a real economic cost of owning the assets. Mineral Vault’s public materials note a rough rule of thumb of around 3% of annual revenue for property taxes, though the actual amount can vary. On top of that, Mineral Vault LLC receives a 10% management fee for ongoing property management, administration, tax and regulatory work, token management, and investor coordination.

In Mineral Vault’s own explanation of the distribution flow, the remaining 90% of net revenue becomes the dividend pool distributed to token holders. That means a month with strong gross receipts can still produce a somewhat different net distribution depending on the exact mix of expenses, taxes, and timing adjustments that landed in that cycle.

U.S. withholding tax is another important consideration. Mineral Vault has disclosed that U.S. source income is initially subject to withholding at the SPV level, with filings and potential recoupment handled as part of the structure. For investors, that means there can be a difference between pre-withholding economics and the amount ultimately available on a net basis.


Portfolio Scale Can Help Smooth the Ride

A single well bet can be extremely binary. If that one well underperforms, goes offline, or declines faster than expected, the investor feels the full impact immediately. A large royalty portfolio behaves differently. With thousands of wells, multiple basins, and more than 150 operators, no single well or operator determines the whole outcome.

This does not eliminate volatility. It changes its character. In a diversified royalty portfolio, some wells are declining while others are stable. Some operators are making payments this month while others are slightly later. Some parts of the portfolio benefit more from oil strength, while others are more sensitive to natural gas pricing. The result is not a flat line, but it can be a more resilient income stream than a concentrated single-asset exposure.

This diversification is one of the most important reasons not to overreact to any single monthly figure. The portfolio should be understood as a living collection of producing assets rather than as one decline curve.


Reserve Replacement Can Become a Material Driver

Aside from the obvious factors of prices, volumes, and timing, reserve replacement becomes increasingly important in a portfolio of this size. Oil and gas wells naturally deplete over time. Mineral Vault has been direct about that reality. Production volumes and cash flow are expected to decline over the 15-year term, which is one of the reasons the offering itself is term-limited.

But depletion is not the whole story. Additional wells may be drilled on existing acreage, new production streams can come online, and presently unleased acreage can generate lease bonuses or later drilling activity. Mineral Vault’s public materials explicitly highlight the future drilling potential on more than 10,000 gross acres as a source of both expected and unexpected additional cash flow.

In a portfolio this large, that matters. A single well declines on its own schedule. A large portfolio has the potential for a more dynamic profile because older wells can be partially offset by new wells entering the asset base over time. Reserve replacement does not eliminate depletion, and it should not be described that way. What it can do is lessen the overall depletion rate of the portfolio by continually adding new productive life into the system as fresh wells come online.

That is one of the most important differences between a one-well investment and a broadly diversified royalty portfolio. The latter is still a depleting real asset, but the aggregate decline profile can be materially softer than the decline profile of any single underlying well.


From Net Revenue to Wallet

After revenue is collected and the applicable deductions are accounted for, Mineral Vault converts the distributable amount into USDC and pays it directly to token holders’ wallets. The mechanics of that step are modern, but the economics underneath are still anchored to real mineral interests, real operator payments, and real portfolio performance.

That is an important distinction. Tokenization does not remove commodity price exposure. It does not stop wells from depleting. It does not create artificial yield. What it does is make ownership easier to access, payout delivery more efficient, and reporting substantially more transparent than what investors have historically seen in private energy investing.


Why Transparency Matters When Distributions Move

A variable distribution model only works for investors if they can understand what is driving the variation. That is where Mineral Vault’s transparency framework matters. Dividend reports, supporting documentation, revenue support, expense support, and public-facing summaries all help connect the final distribution amount back to the underlying economics of the portfolio.

In traditional royalty investing, investors often had to wait for paper checks, mailed statements, delayed tax forms, and fragmented reporting. Mineral Vault’s model is stronger because it pairs real producing mineral interests with direct-to-wallet distributions and a much clearer reporting trail. That does not make every month identical. It makes every month more understandable.


The Right Way to Read a Monthly Distribution

The best way to evaluate a royalty distribution is not to ask whether it stayed flat. It is to ask what happened across the portfolio. Were commodity prices stronger or weaker? Were production volumes up or down? Did payment timing shift? Were there any one-time bonuses, taxes, or deductions? Were new wells helping offset legacy decline?

For Mineral Vault I, monthly distributions are the output of a real asset system, not a fixed-income abstraction. That is exactly what makes them interesting. Investors are receiving cash flow tied to U.S. energy production, while benefiting from diversification, tokenized access, direct-to-wallet distributions, and unusually robust transparency. Month-to-month variability is part of that reality. The goal is not to eliminate it. The goal is to understand it.

Why Private Mineral Ownership Is So Rare Globally – And Why That Matters

When most people think about oil, gas, and other valuable underground resources, they picture governments, national oil companies, and state-controlled licensing regimes. In most of the world, that is the correct mental model. The subsurface belongs to the state, and private parties participate only through concessions, leases, joint ventures, or service contracts granted by the government.

That is precisely why the United States remains so unusual. Here, mineral rights can be privately owned, sold, inherited, severed from the surface estate, and leased to operators in exchange for royalties. That legal structure created an investable market that is rare on a global scale: a market where private owners can hold long-duration rights to underground resources and receive income when those resources are developed.

For Mineral Vault, that is not just an interesting legal footnote. It is the foundation of our asset class. Private mineral ownership is what makes American oil and gas royalties both so compelling and so historically difficult to access. And once investors understand why this ownership model is rare, they also understand why bringing it on-chain matters.


The global rule: governments control the subsurface

Across much of the world, subsurface resources are treated as sovereign assets. Even when surface land is privately owned, the oil, gas, or mineral estate below it is often reserved to the national or regional government. Companies can still explore and produce, but they do so through state-issued rights, negotiated contracts, and regulatory frameworks that do not create the same large-scale private ownership market seen in parts of the United States.

This matters because it changes the entire ownership chain. In a state-dominant system, investors usually gain exposure through public equities, sovereign-linked ventures, production-sharing agreements, debt instruments, or direct corporate ownership in operating companies. What they generally do not gain is a broad market of privately owned mineral interests that can be aggregated, transferred, leased, and monetized over decades the way U.S. mineral properties can.

That is why private mineral ownership at scale is so rare globally. It is not simply a matter of geology. It is a matter of property law, legal history, and the way different countries chose to allocate economic rights in natural resources.


The U.S. exception: a private market in the mineral estate

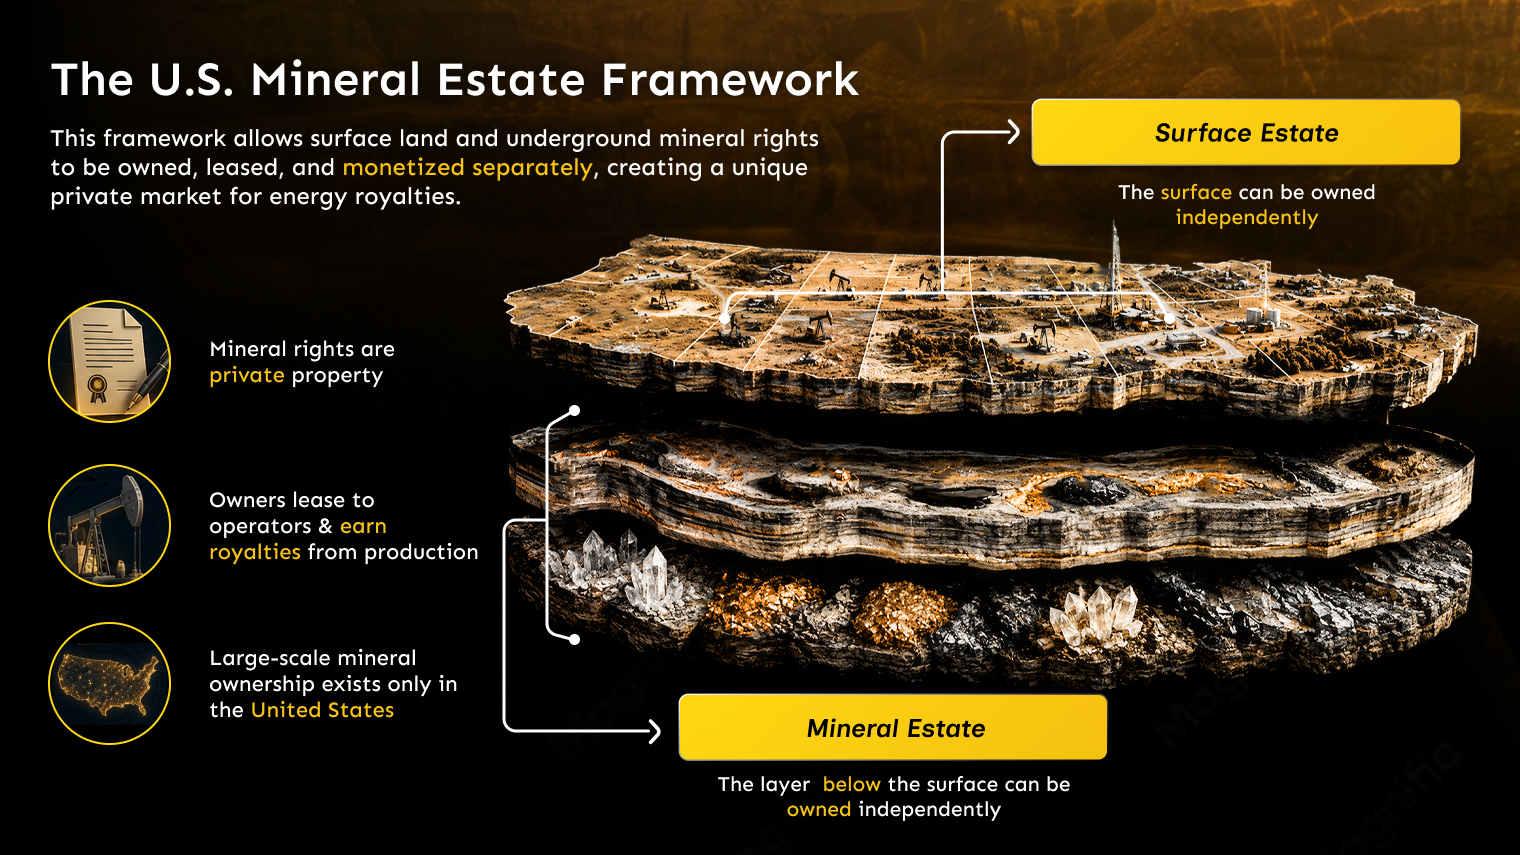
The United States developed a very different framework. In most producing regions, the mineral estate can be treated as a separate form of real property. That means the rights below the ground can be owned independently from the surface above it. A parcel can therefore have one owner for the surface and another for the minerals. Those mineral rights can be sold, transferred, inherited, and leased in their own right.

That separability is one of the defining features of the asset class. In practical terms, it means mineral owners do not have to drill wells themselves to benefit economically. They can lease their mineral interests to operators, collect an upfront lease bonus in many cases, and then receive an ongoing royalty tied to production if development occurs. In other words, they own the property interest while the operator takes on the capital-intensive work of drilling, completing, and producing the well.

This is also why mineral and royalty interests have long occupied a category of their own:

  • They share some traits with real estate, because they are real property interests.
  • They share some traits with income assets, because they can generate recurring cash flow.
  • They share some traits with commodity-linked derivatives, because revenue rises and falls with production volumes and commodity prices.

…but mineral and royalty interests are not reducible to any one of these buckets.

It is important to keep the nuance intact here. Not every mineral resource in the United States is privately owned. Federal lands, many state-owned lands, tribal lands, and offshore federal resources follow different legal frameworks. The point is not that every American resource is private. The point is that the United States has a deep and scalable private minerals market – especially onshore – that is unusual among major producing nations.


Why this rarity creates both value and friction

Whenever an asset class is both economically attractive and structurally unusual, two things tend to happen at once: the asset becomes valuable, and access becomes messy. That is exactly what happened in mineral interests.

On the value side, private mineral ownership gives investors direct participation in American energy production without requiring them to operate wells. When high-quality mineral interests are leased and producing, owners can receive long-duration royalty income with meaningful inflation linkage because hydrocarbons are sold into real commodity markets. In many structures, the mineral owner also avoids most of the drilling and operating costs borne by the operator.

On the friction side, the market developed in a way that was highly fragmented, paper-heavy, and relationship-driven. Mineral rights have often passed through generations, trusts, estates, family partitions, and thousands of individual transactions. Ownership records can be scattered across county courthouses and title files. Minimum investment sizes have historically been high. Liquidity has been limited. And for investors outside the United States, the barriers have been even higher because the asset class itself is so tied to a uniquely American property system.

This combination is exactly why mineral interests have remained under-owned by the broader global investment market. It is not because the cash flow characteristics are weak. It is because the access path has traditionally been too narrow, too technical, and too operationally burdensome for most investors to navigate.


Why it matters to investors

For investors, the global rarity of private mineral ownership matters because rarity shapes portfolio opportunity. If an asset class exists at scale in only one major jurisdiction, and if access to that asset class has historically been difficult, then the investors who can access it efficiently may be seeing a genuinely differentiated source of return.

Mineral and royalty interests provide exposure to real-world production cash flow rather than to the earnings of an operator or the coupon stream of a bond. They can offer monthly income, inflation-sensitive revenue, long-duration underlying property exposure, and upside from future leasing or drilling activity on the acreage. At the same time, they are not the same thing as direct working interests in wells, where capital calls and operating costs can materially change the risk profile.

That distinction matters even more in a modern portfolio. Many investors already understand stocks, bonds, and listed real estate. Far fewer have access to a real-asset income stream tied directly to U.S. energy production while remaining generally non-cost-bearing at the mineral-owner level. That is part of what makes the asset class so compelling once it can be accessed cleanly.


Why it matters to Mineral Vault

Mineral Vault was built around the idea that a rare, high-quality asset class becomes dramatically more powerful when access frictions are reduced. Mineral Vault I brings together a large, diversified portfolio of U.S. mineral and royalty interests spanning more than 2,500 producing wells, more than 10,000 gross acres, 150-plus operators, and 9 U.S. states. That scale matters because it moves investors away from the concentration risk of a single property or operator and toward a broader stream of American energy cash flow.

Just as importantly, Mineral Vault does not present mineral ownership as a novelty. It presents it as infrastructure for a better investment experience. Through tokenization, a historically fragmented and paper-based market can be transformed into a digital ownership record with clearer provenance, lower administrative friction, easier transferability within the applicable compliance framework, and monthly digital distributions tied to real underlying cash flow.

That bridge from old-world property rights to modern financial rails is what makes the topic so relevant today. The underlying legal foundation is not new. Private mineral ownership in the U.S. has existed for generations. What is new is the ability to package that ownership into a structure that is more transparent, more accessible, and more usable for a broader class of investors, including investors outside the traditional U.S. mineral-rights ecosystem.


Historically, if a global investor wanted exposure to U.S. mineral interests, the practical obstacles were substantial. The investor had to understand title, legal documentation, jurisdictional structuring, operator reporting, cash distribution mechanics, and a market that often moved through specialist networks rather than broad digital marketplaces. Even sophisticated investors frequently chose not to engage, not because the asset class lacked merit, but because the ownership system was too inefficient.

Tokenization changes that equation. Once the underlying mineral interests are properly aggregated and structured, digital ownership records can replace much of the transfer friction that made the asset class so cumbersome. On-chain records can improve provenance after issuance and transfer. Compliance tooling can help preserve lawful access pathways. Reporting can become more standardized and more visible. And cash flow can be distributed in a way that better matches the expectations of modern digital investors.

This is where the rarity of private mineral ownership becomes more than an interesting educational topic. It becomes a strategic advantage. If the United States is one of the only places where this type of asset exists at meaningful scale, and if Mineral Vault can make that asset class more legible and accessible to a global audience, then tokenization is not a cosmetic wrapper. It is the enabling layer that converts a rare property-rights system into an investable digital experience.


A more precise way to think about the opportunity

It is tempting to reduce the story to a simple headline: the U.S. is unique, therefore mineral royalties are valuable. But the better way to think about it is more specific. The rarity matters because it concentrates a distinctive ownership model inside one major market. That ownership model produces a real-asset income stream that most global investors have never had efficient access to. And because access has been so inefficient, the market has historically remained narrower than the underlying economic value would suggest.

Mineral Vault exists to close that gap. By combining professionally managed U.S. mineral and royalty interests with blockchain-native issuance, transparent reporting, and digital distributions, Mineral Vault is not inventing a new asset class. It is opening an old and highly differentiated one to a modern investor base.


Final Thoughts

Private mineral ownership is rare globally because most legal systems reserve subsurface value for the state. The United States developed differently, creating a market where mineral rights can be privately held, leased, and monetized at scale. That difference has made American mineral interests both powerful and hard to reach.

Why does that matter? Because rare ownership structures create rare investment opportunities – but only if investors can actually access them. Mineral Vault is built on the belief that U.S. mineral and royalty interests deserve a broader audience, and that tokenization can finally provide the access layer this asset class has always lacked.

In that sense, the story is larger than mineral rights alone. It is about what happens when a uniquely American property system meets global digital finance. And that is exactly where the next chapter of this asset class begins.